
Latham trades at $6.14 and has moved in lockstep with the market. Its shares have returned 18.8% over the last six months while the S&P 500 has gained 21.1%.
Is there a buying opportunity in Latham, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Latham Will Underperform?
We’re passing on Latham for now. Here are three reasons why SWIM doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
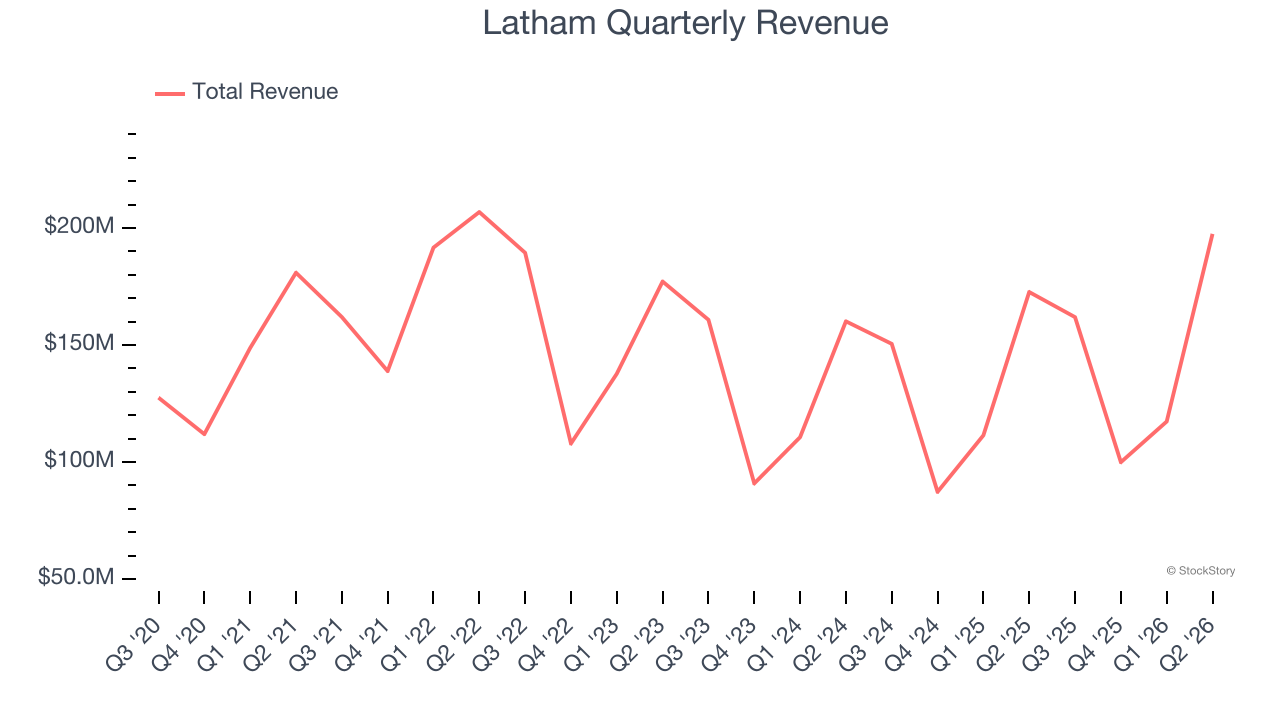
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Latham struggled to consistently increase demand as its $576.6 million of sales for the trailing 12 months was close to its revenue five years ago. This wasn’t a great result and is a sign of poor business quality.
2. Cash Flow Margin Set to Decline
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts predict Latham’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 6.4% for the last 12 months will decrease to 3.7%.
3. New Investments Bear Fruit as ROIC Jumps
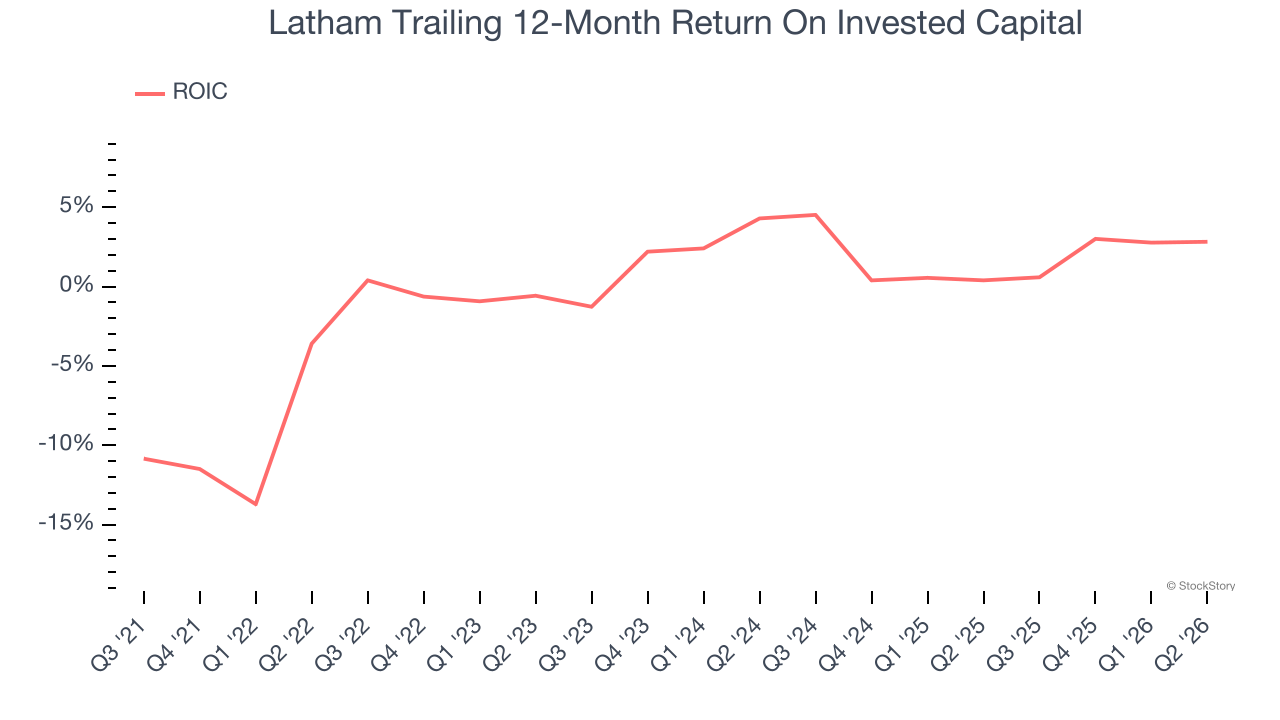
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
On average, Latham’s ROIC increased by 3.7 percentage points annually each year over the last few years. This is a good sign, and we hope the company can continue improving.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Latham, we’ll be cheering from the sidelines. That said, the stock currently trades at 24.1× forward P/E (or $6.14 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better stocks to buy right now. We’d suggest looking at one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.