Henry Schein trades at $86.39 and has moved in lockstep with the market. Its shares have returned 18.8% over the last six months while the S&P 500 has gained 21.4%.
Is now the time to buy Henry Schein, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Henry Schein Not Exciting?
We’re cautious about Henry Schein. Here are three reasons you should be careful with HSIC, plus one stock we’d rather own.
1. Slow Organic Growth Suggests Waning Demand In Core Business
We can better understand Dental Equipment & Technology companies by analyzing their organic revenue. This metric gives visibility into Henry Schein’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Henry Schein’s organic revenue averaged 2.9% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 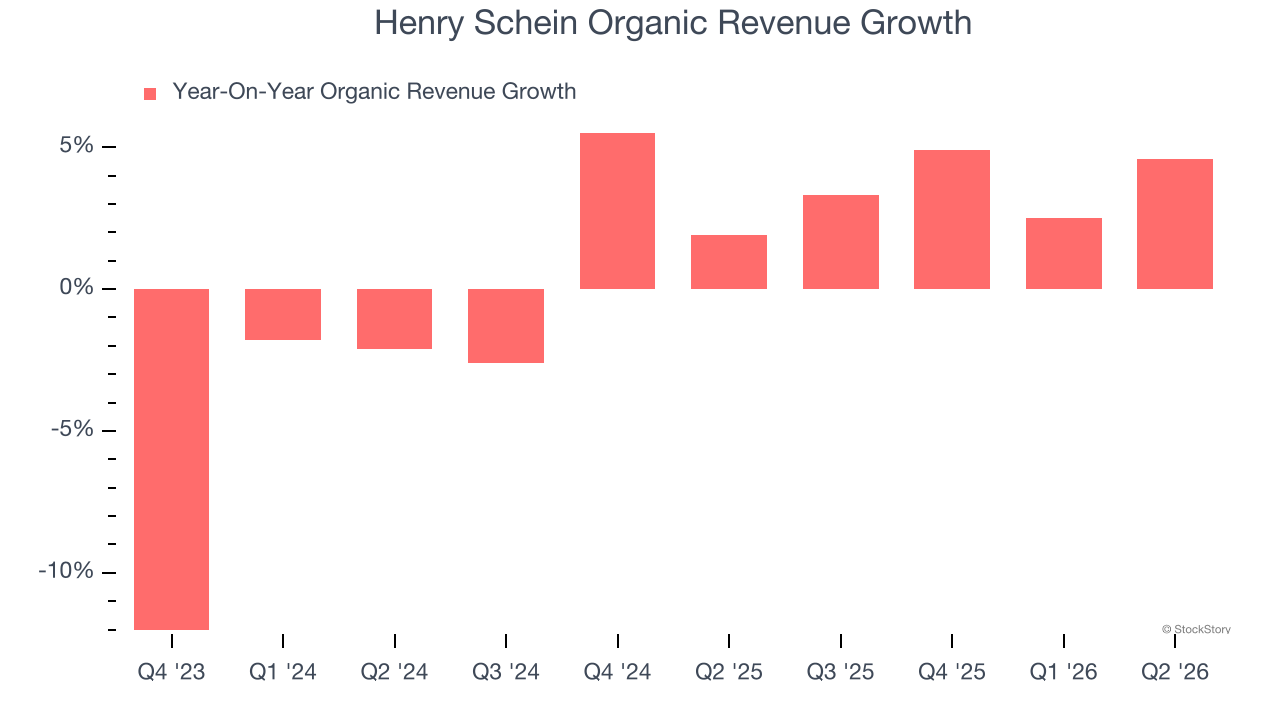
2. EPS Barely Growing
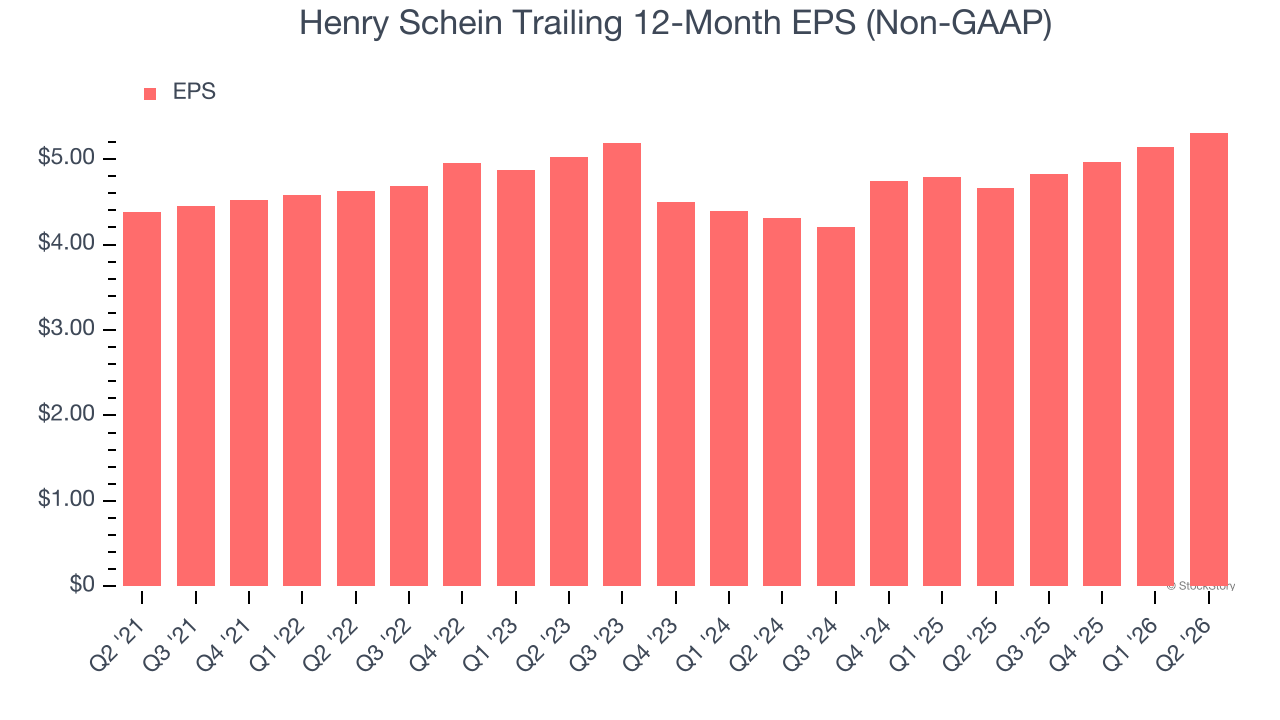
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Henry Schein’s unimpressive 3.9% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
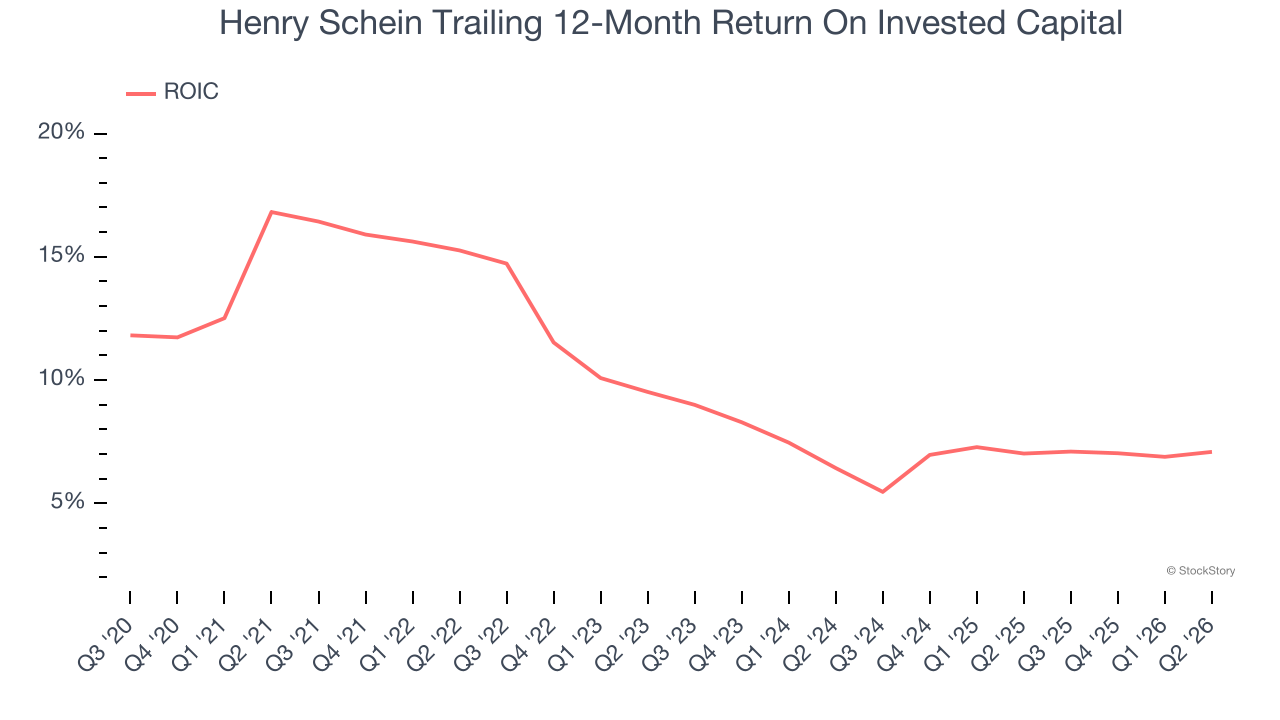
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Henry Schein’s ROIC has decreased over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Henry Schein isn’t a terrible business, but it doesn’t pass our quality test. That said, the stock currently trades at 15.1× forward P/E (or $86.39 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at the Amazon and PayPal of Latin America.
Stocks We Like More Than Henry Schein
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.