What a brutal six months it’s been for Tractor Supply. The stock has dropped 31.8% and now trades at $31.37, rattling many shareholders. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Tractor Supply, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Tractor Supply Not Exciting?
Even though the stock has become cheaper, we don’t have much confidence in Tractor Supply. Here are three reasons we avoid TSCO, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
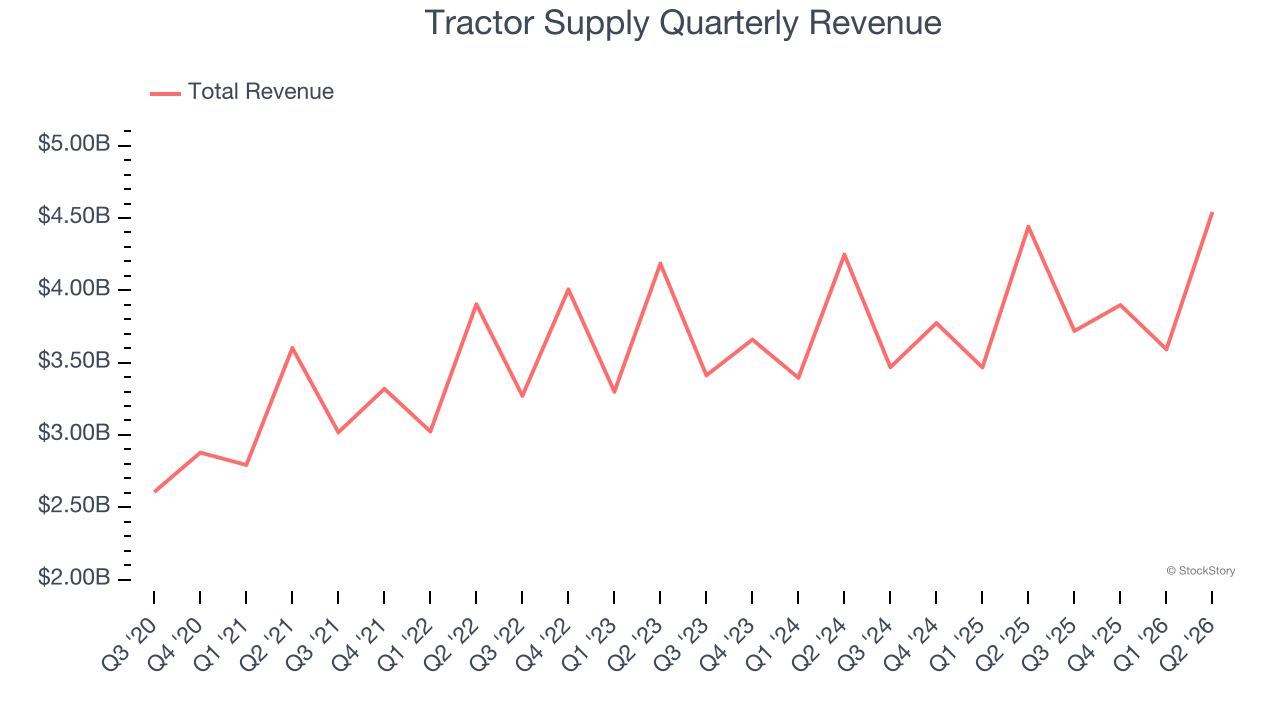
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Regrettably, Tractor Supply’s sales grew at a sluggish 2.2% compounded annual growth rate over the last three years. This was below our standards.
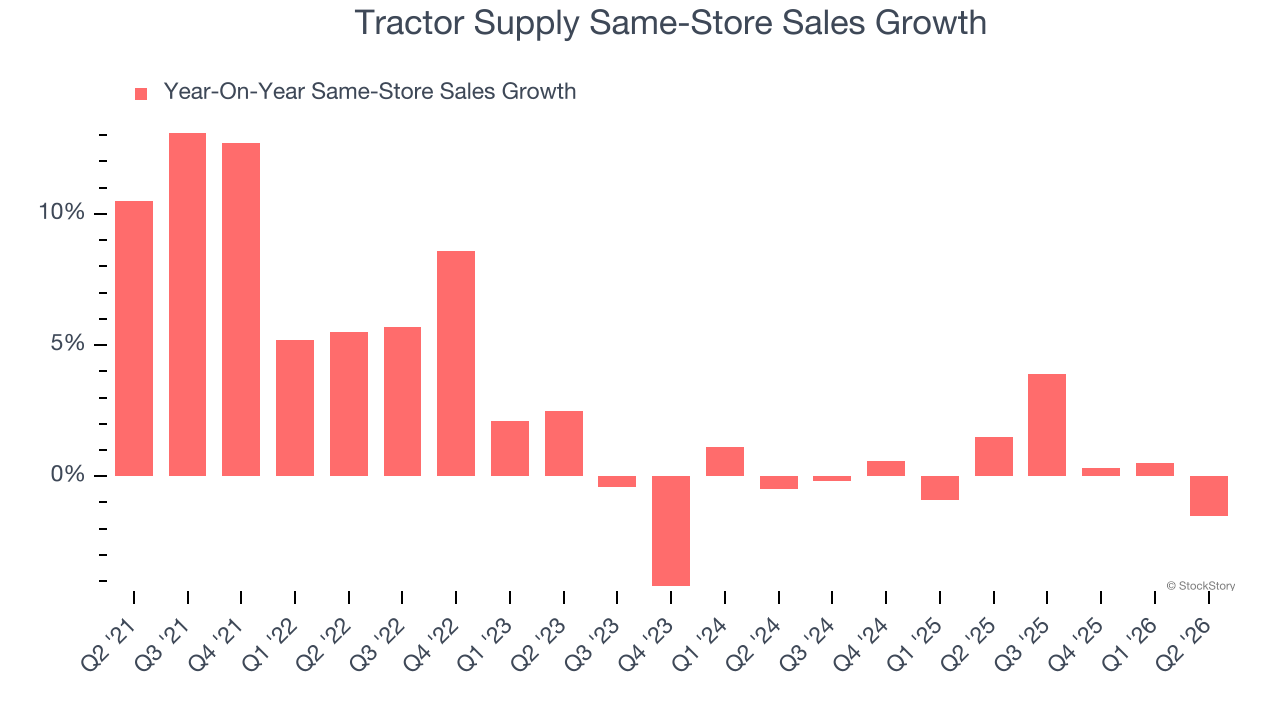
2. Flat Same-Store Sales Indicate Weak Demand
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Tractor Supply’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat.
3. Free Cash Flow Margin Dropping
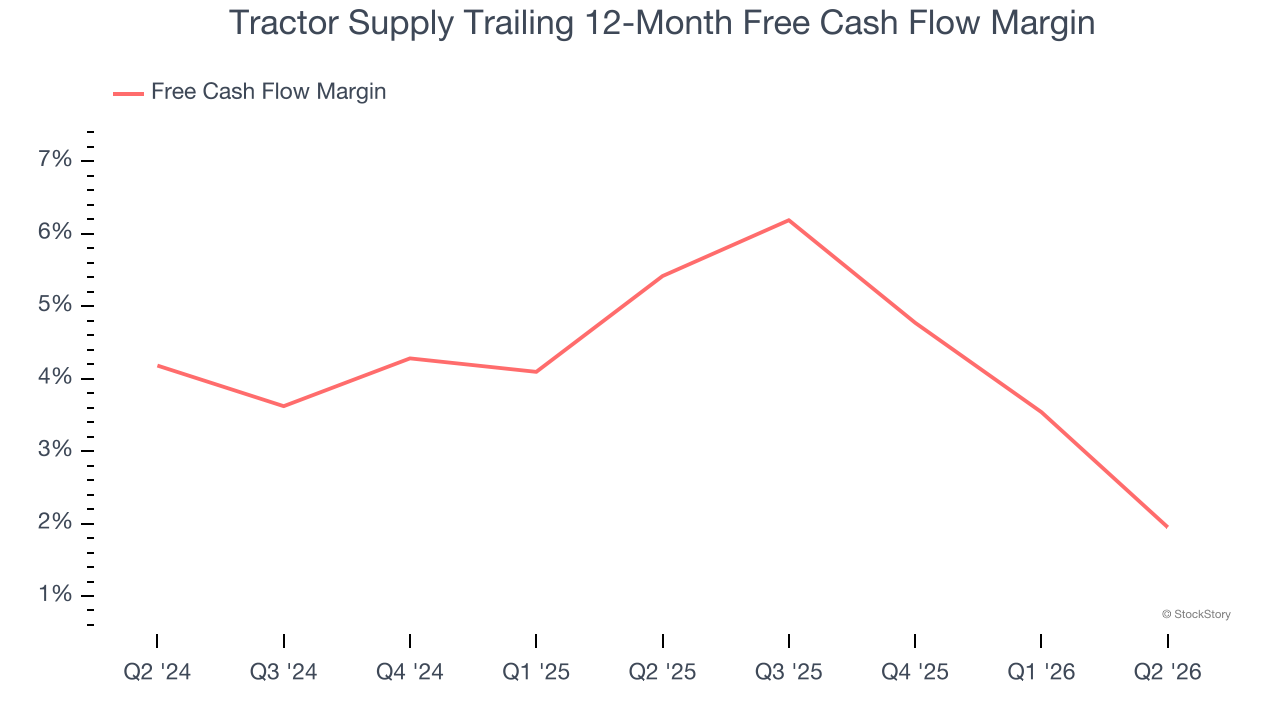
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Tractor Supply’s margin dropped by 3.5 percentage points over the last year. This decrease came from the higher costs associated with opening more stores.
Final Judgment
Tractor Supply’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 16.4× forward P/E (or $31.37 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of Tractor Supply
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.