Technology distribution company ScanSource (NASDAQ: SCSC) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 30.1% year on year to $962.3 million. The company’s full-year revenue guidance of $3.9 billion at the midpoint came in 7.1% above analysts’ consensus estimates. Its non-GAAP profit of $0.86 per share was 23.1% below analysts’ consensus estimates.
For more on ScanSource, read our free full research report.
ScanSource (SCSC) Q3 2026 highlights:
- Revenue $962.3 million vs S&P analysts’ consensus estimates of $861.2 million (30.1% year-on-year growth, 11.7% beat)
- Adjusted EPS $0.86 vs S&P analysts’ consensus estimates of $1.12 (23.1% miss)
- Adjusted EBITDA $31.3 million vs analysts’ consensus estimates of $39.17 million (3.3% margin, 20.1% miss)
- EBITDA guidance $180 million at the midpoint for the full year, above analysts’ consensus estimates of $170.8 million
- Operating margin 1.3%, down from 3.6% in the same quarter last year
- Free cash flow -$44.15 million, down from $20.82 million in the same quarter last year
- Market capitalization $1.15 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $3.45 billion in revenue over the past 12 months, ScanSource is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale.
ScanSource’s 1.2% annualized revenue growth over the last five years was sluggish. This shows it failed to generate substantial demand.
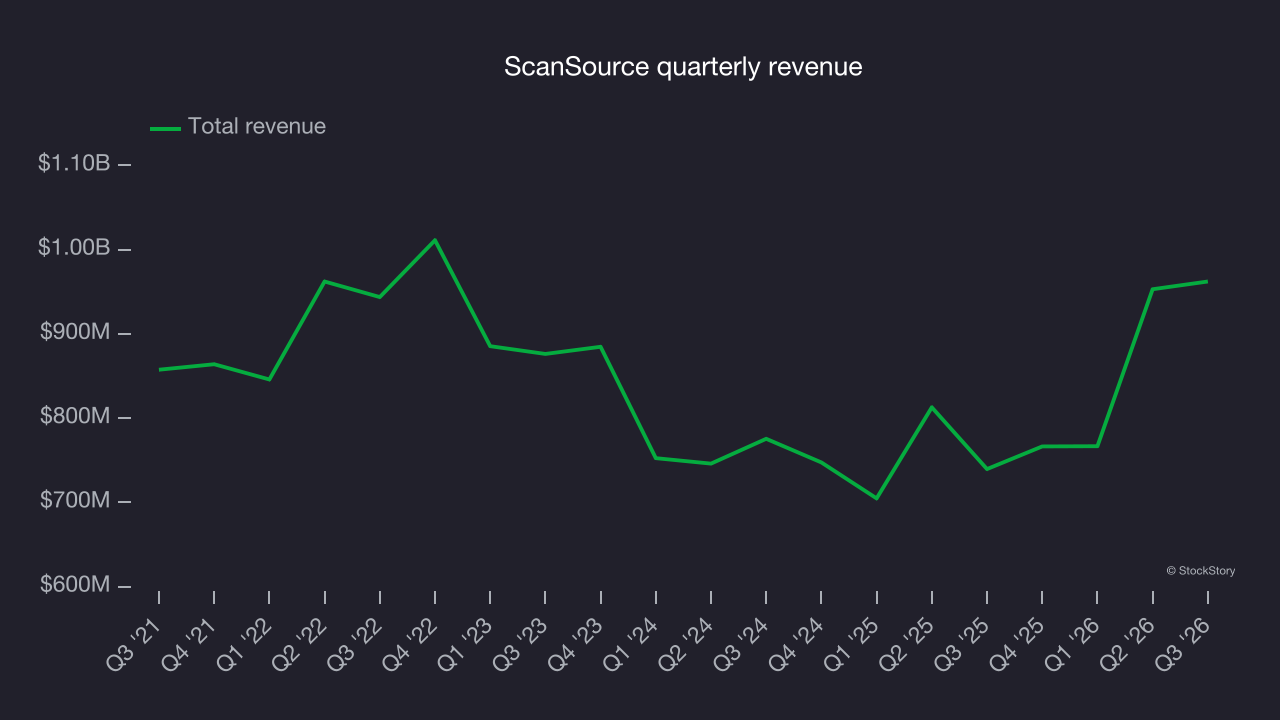
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. ScanSource’s annualized revenue growth of 4.5% over the last two years is above its five-year trend, a positive sign.
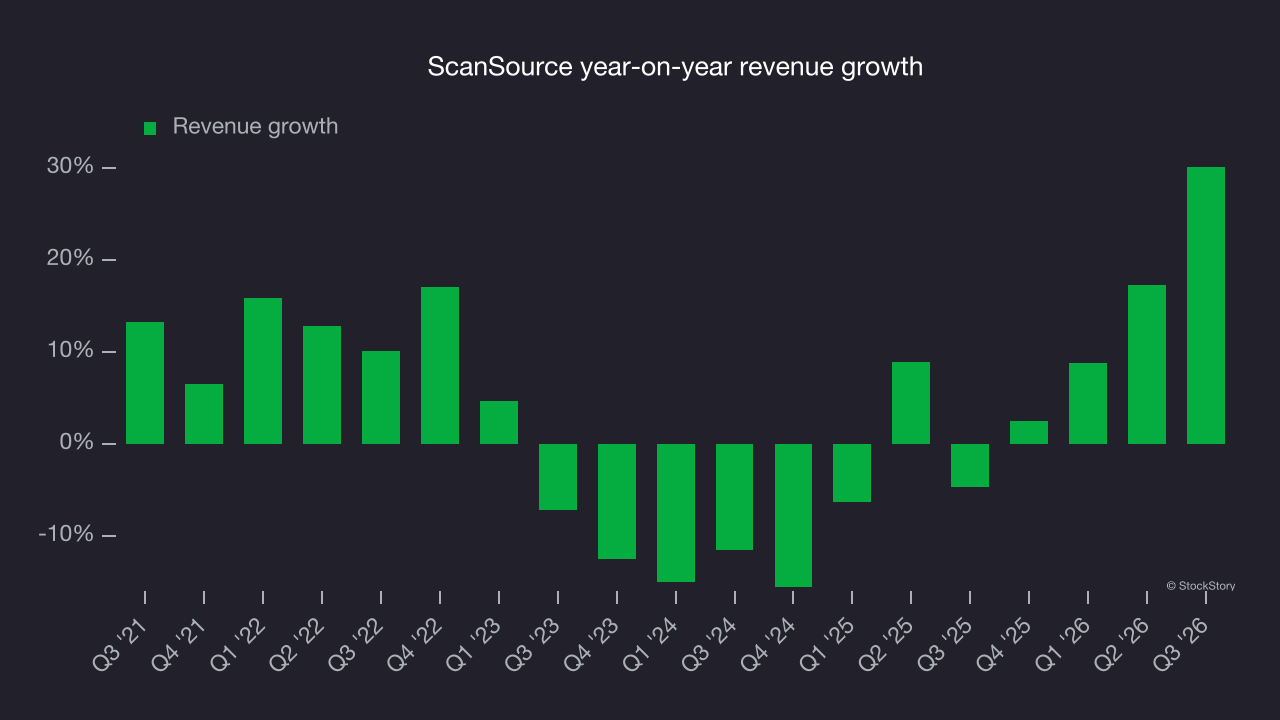
This quarter, ScanSource reported strong year-on-year revenue growth of 30.1%, and its $962.3 million in revenue exceeded Wall Street’s consensus estimates by 11.7%.
Looking ahead, sell-side analysts expect revenue to grow 7.9% over the next 12 months, according to S&P, an improvement versus the last two years. This positive outlook implies its newer products and services will drive better revenue performance.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
ScanSource’s adjusted operating margin has generally stayed the same over the last 12 months, averaging 3.5% over the last five years. This profitability was poor for a business services company, reflecting its suboptimal cost structure.
ScanSource’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
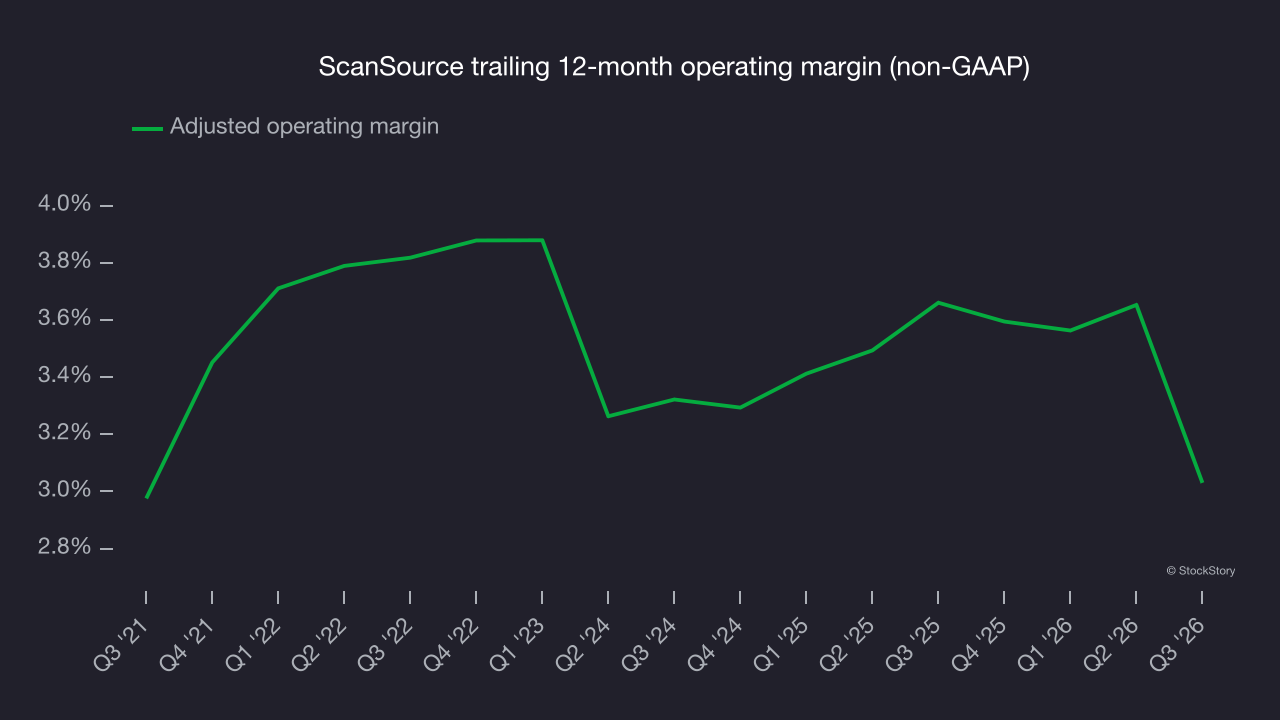
This quarter, ScanSource generated an adjusted operating margin of 1.7%, down 2.3 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
ScanSource’s EPS grew at a 4.2% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its adjusted operating margin improvement was smaller than that of its peers.
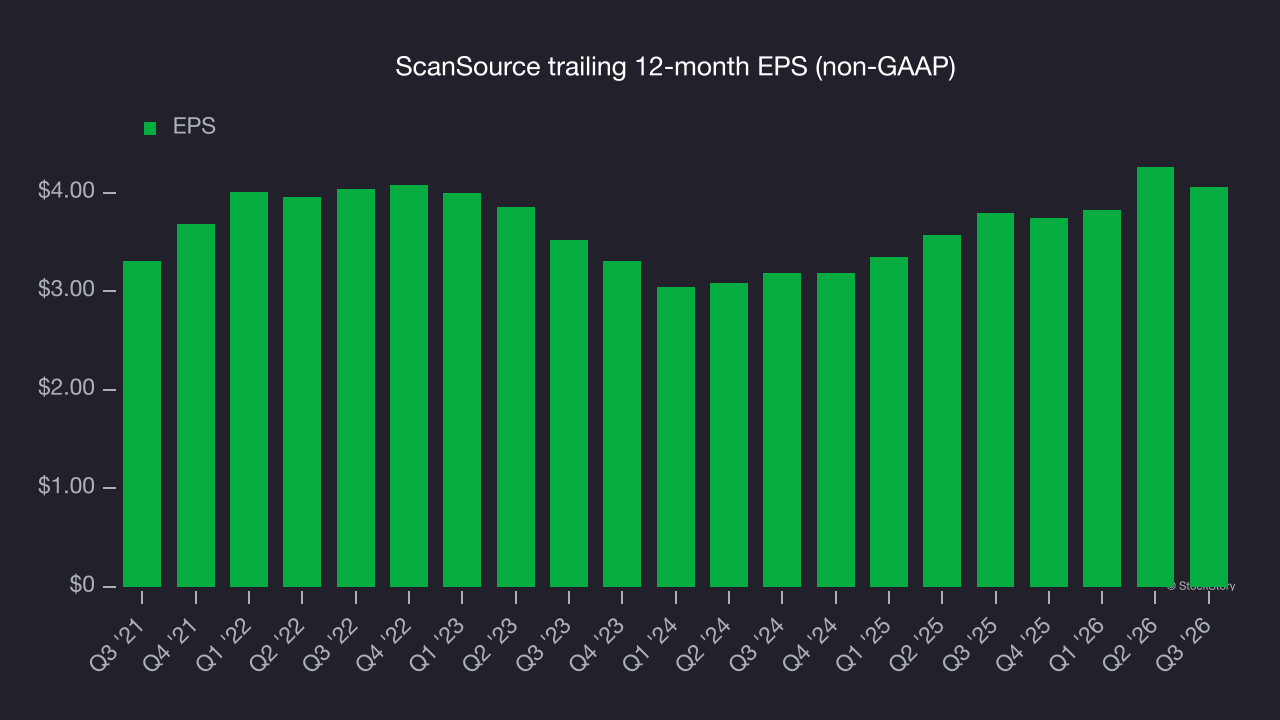
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For ScanSource, its two-year annual EPS growth of 13% was higher than its five-year trend. This acceleration made it one of the faster-growing business services companies in recent history.
In Q3, ScanSource reported adjusted EPS of $0.86, down from $1.06 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects ScanSource’s full-year EPS to grow 24.2% from $4.06 to $5.04, according to S&P.
Key takeaways from ScanSource’s Q3 results
ScanSource delivered a sizable revenue beat and full-year revenue guidance above Wall Street’s consensus estimates, giving the quarter some key positives. But EBITDA and EPS missed expectations quite meaningfully. Investors were likely hoping for more, and shares edged lower 1.6% to $56.04 immediately after the results.
When evaluating ScanSource at its current price, consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).