Network chipmaker MACOM Technology Solutions (NASDAQ: MTSI) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 (fiscal Q4 2026), with revenue up 62.7% year on year to $424.8 million. In addition, next quarter’s revenue guidance ($455 million at the midpoint) was surprisingly strong, coming in 5.4% above analysts’ consensus estimates. Its non-GAAP profit of $2.09 per share was 4.5% above analysts’ consensus estimates.
For more on MACOM, read our full research report, available free.
MACOM (MTSI) Q3 CY2026 highlights:
- Revenue $424.8 million vs S&P analysts’ consensus estimates of $420.4 million (62.7% year-on-year growth, 1% beat)
- Adjusted EPS $2.09 vs S&P analysts’ consensus estimates of $2.00 (4.5% beat)
- Adjusted EBITDA $171.5 million vs analysts’ consensus estimates of $170.7 million (40.4% margin, in line)
- Revenue guidance $455 million at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $431.6 million
- Adjusted EPS guidance $2.25 at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $2.03
- Operating margin 31.6%, up from 15.2% in the same quarter last year
- Free cash flow margin 32.5%, up from 18.9% in the same quarter last year
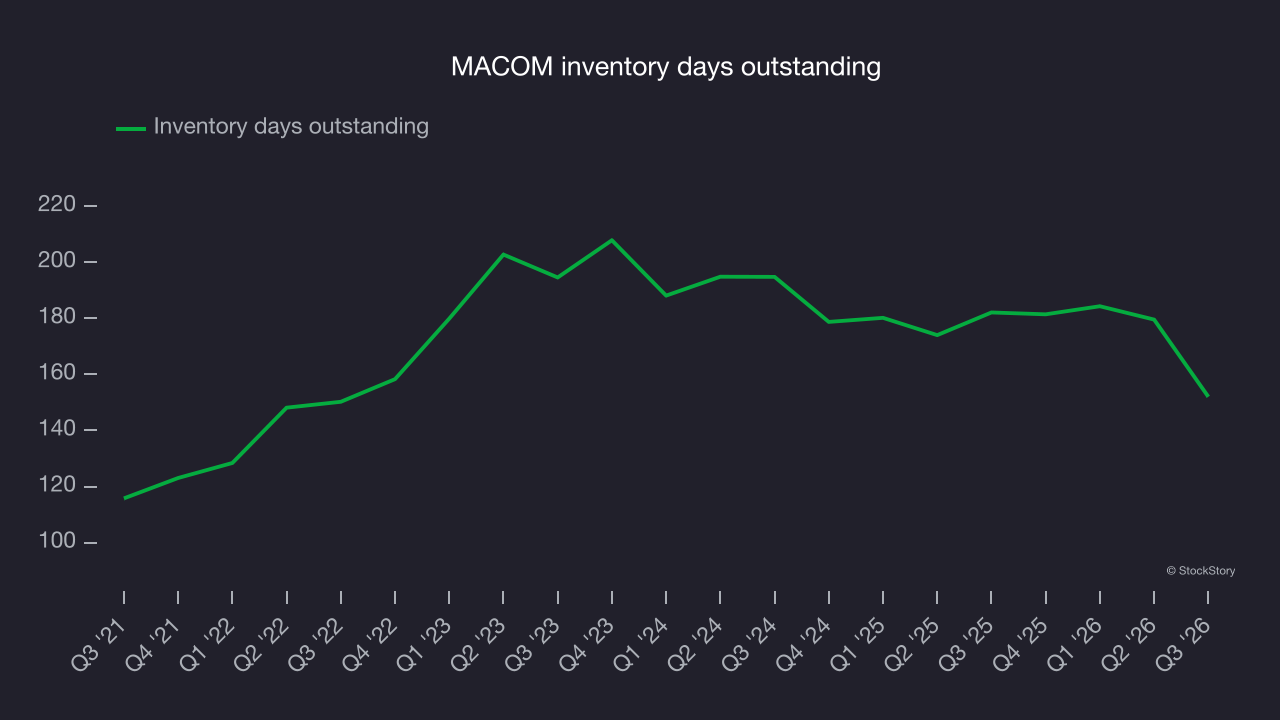
- Inventory days outstanding 152, down from 180 in the previous quarter
- Market capitalization $17.8 billion
“We had a strong fiscal year 2026 and look forward to continued growth in fiscal 2027,” said Stephen G. Daly, President and Chief Executive Officer, MACOM.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. MACOM’s 16.9% annualized revenue growth over the last five years was strong. Its growth beat the average semiconductor company and shows its offerings resonate with customers. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
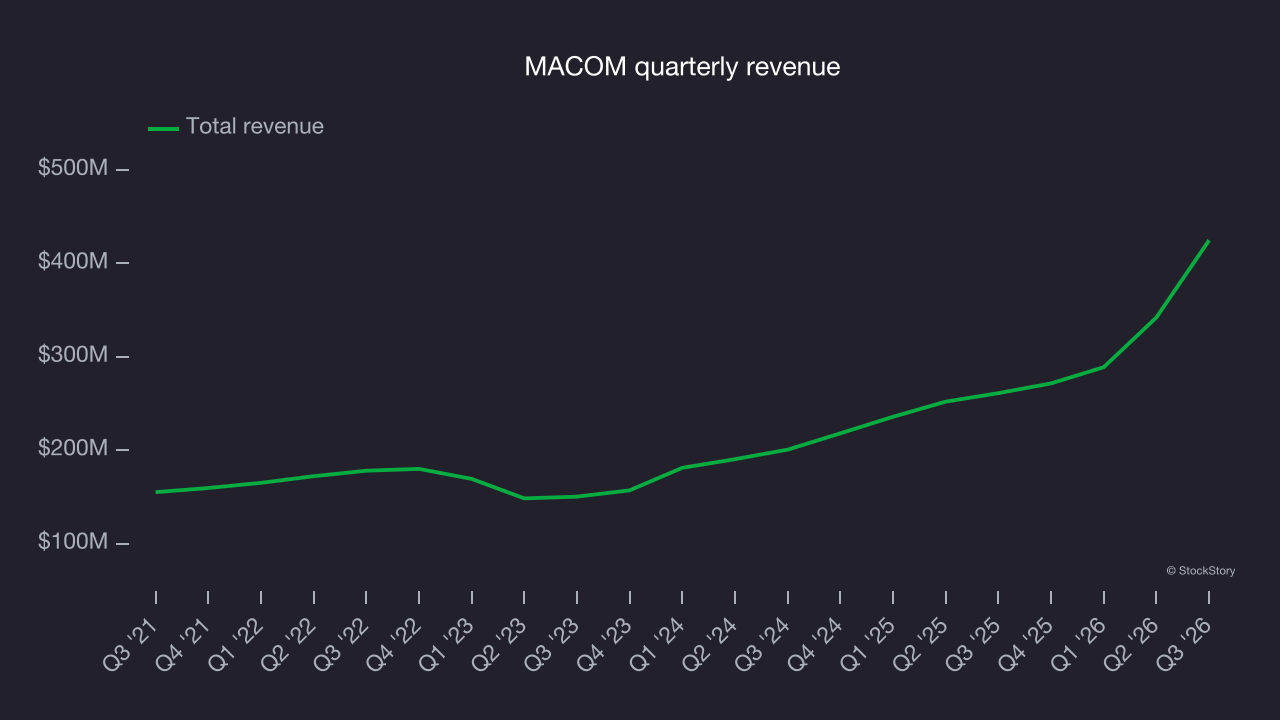
Long-term growth matters the most, but within semiconductors, a half-decade historical view may miss new demand cycles or industry trends like artificial intelligence. MACOM’s annualized revenue growth of 34.9% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated.
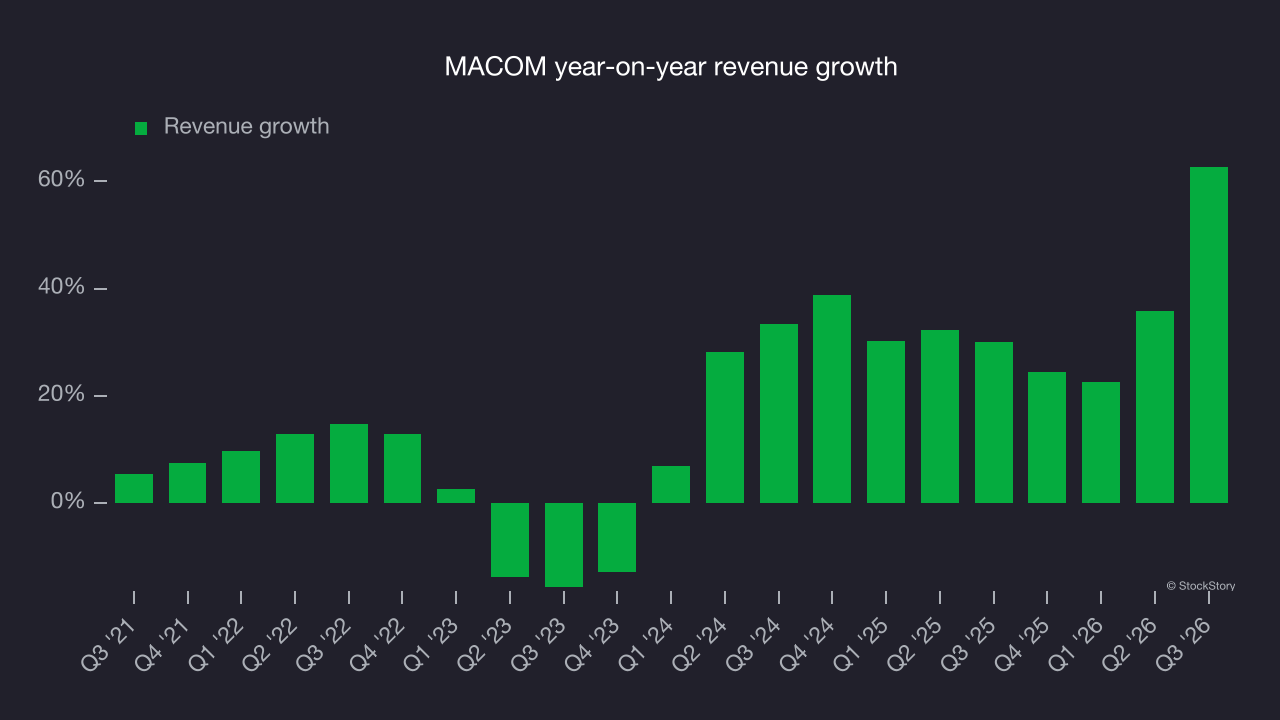
This quarter, MACOM reported strong year-on-year revenue growth of 62.7%, and its $424.8 million in revenue beat Wall Street’s consensus estimates by 1%. Beyond the beat, this marks 11 straight quarters of growth, showing that the current upcycle has been sustained longer than the typical 8 to 10 quarters. Company management is currently guiding for a 67.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 35.5% over the next 12 months, according to S&P, similar to its two-year rate. This projection is above average for the sector and implies its newer products and services will help maintain its recent top-line performance.
Product demand & outstanding inventory
Days inventory outstanding, or DIO, is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, MACOM’s DIO came in at 152, which is 22 days below its five-year average. At the moment, these numbers show no indication of an excessive inventory buildup.
Key takeaways from MACOM’s Q3 results
MACOM’s inventory levels improved substantially, and its revenue outlook for next quarter topped Wall Street’s consensus estimates, making for a solid quarter. Investors were likely hoping for more: Shares tumbled 6.5% to $218.29 immediately after the results.
Is MACOM worth buying at its current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in the stock. Read the full research report here (it’s free).