ABM has had an impressive run over the past six months as its shares have beaten the S&P 500 by 28%. The stock now trades at $53.30, marking a 32.7% gain. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in ABM, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is ABM not exciting?
We’re glad investors have benefited from the price increase, but we’re passing on ABM for now. Here are three reasons why there are better opportunities than ABM, plus one stock we’d rather own.
1. Slow organic growth suggests waning demand in core business
Investors interested in industrial & environmental services companies should track organic revenue in addition to reported revenue. This metric gives visibility into ABM’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, ABM’s organic revenue averaged 4% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 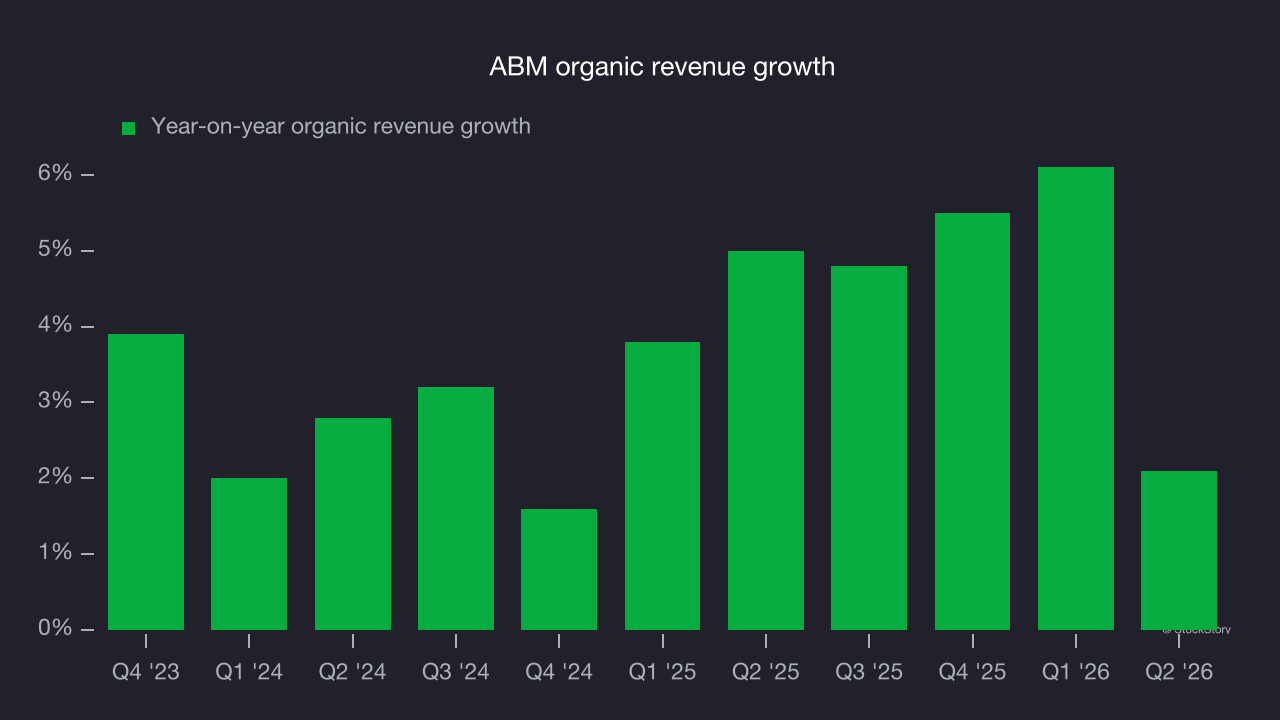
2. EPS barely growing
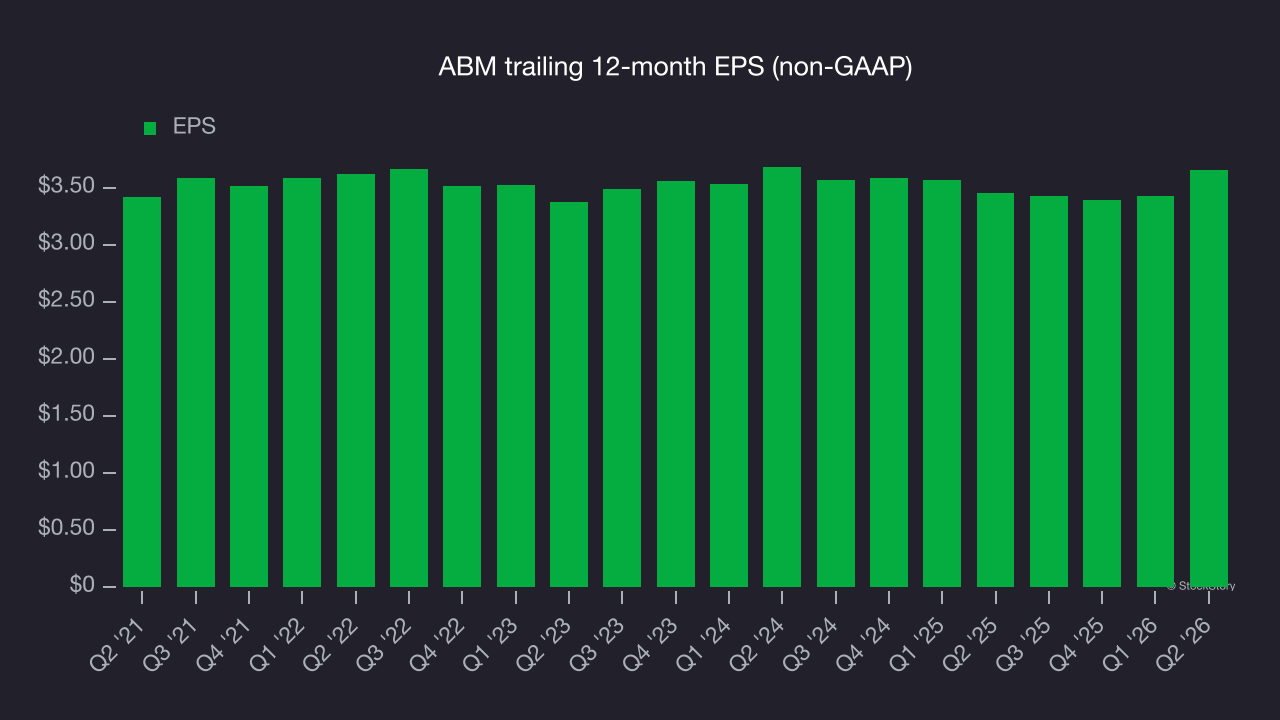
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
ABM’s EPS grew at a weak 1.3% compounded annual growth rate over the last five years, lower than its 8.7% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Mediocre free cash flow margin limits reinvestment potential
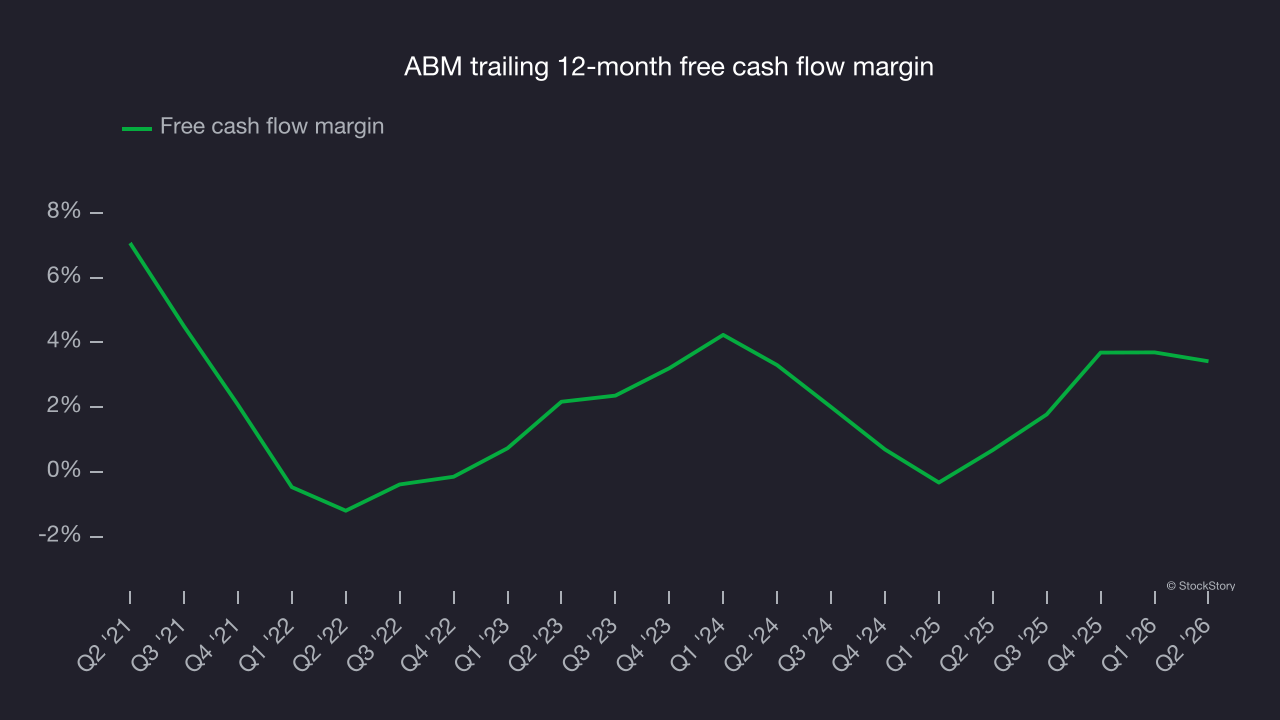
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
ABM has shown poor cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 1.7%, below what we’d expect for a business services business.
Final judgment
ABM isn’t a terrible business, but it isn’t one of our picks. With its shares topping the market in recent months, the stock trades at 12.8× forward P/E (or $53.30 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at one of our top software and edge computing picks.
Stocks we would buy instead of ABM
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.