Agricultural supply chain company Archer-Daniels-Midland (NYSE: ADM) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 9.6% year on year to $22.34 billion. Its non-GAAP profit of $1.77 per share was 10.4% above analysts’ consensus estimates.
For more on Archer-Daniels-Midland, read our free full research report.
Archer-Daniels-Midland (ADM) Q3 2026 highlights:
- Revenue $22.34 billion vs S&P analysts’ consensus estimates of $22.55 billion (9.6% year-on-year growth, 0.9% miss)
- Adjusted EPS $1.77 vs S&P analysts’ consensus estimates of $1.60 (10.4% beat)
- Adjusted EBITDA $1.53 billion vs analysts’ consensus estimates of $1.38 billion (6.8% margin, 10.4% beat)
- Adjusted EPS guidance $5.65 at the midpoint for the full year, beating analysts’ consensus estimates by 2%
- Operating margin 4.2%, up from 1.9% in the same quarter last year
- Free cash flow margin 0.8%, down from 7.4% in the same quarter last year
- Market capitalization $36.52 billion
“ADM delivered strong third quarter results, with earnings up significantly from the prior year quarter and operating profit growth across all segments,” said Juan Luciano, Chair of the Board and Chief Executive Officer. “These results were driven by a constructive biofuels environment combined with our extensive North American footprint, which gives us significant access to premium markets, and good execution by our team. Our year-to-date performance and fourth quarter outlook support another increase to our full-year 2026 adjusted EPS guidance.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term.
With $84.06 billion in revenue over the past 12 months, Archer-Daniels-Midland is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, allowing it to choose where it sells its products, an advantage many companies lack. However, its scale is a double-edged sword because there are only so many big store chains to sell into, making it harder to find incremental growth. To expand meaningfully, Archer-Daniels-Midland likely needs to adjust its prices, innovate with new products or enter new markets.
Archer-Daniels-Midland’s demand was weak over the last three years. Its revenue fell by 4.6% annually.
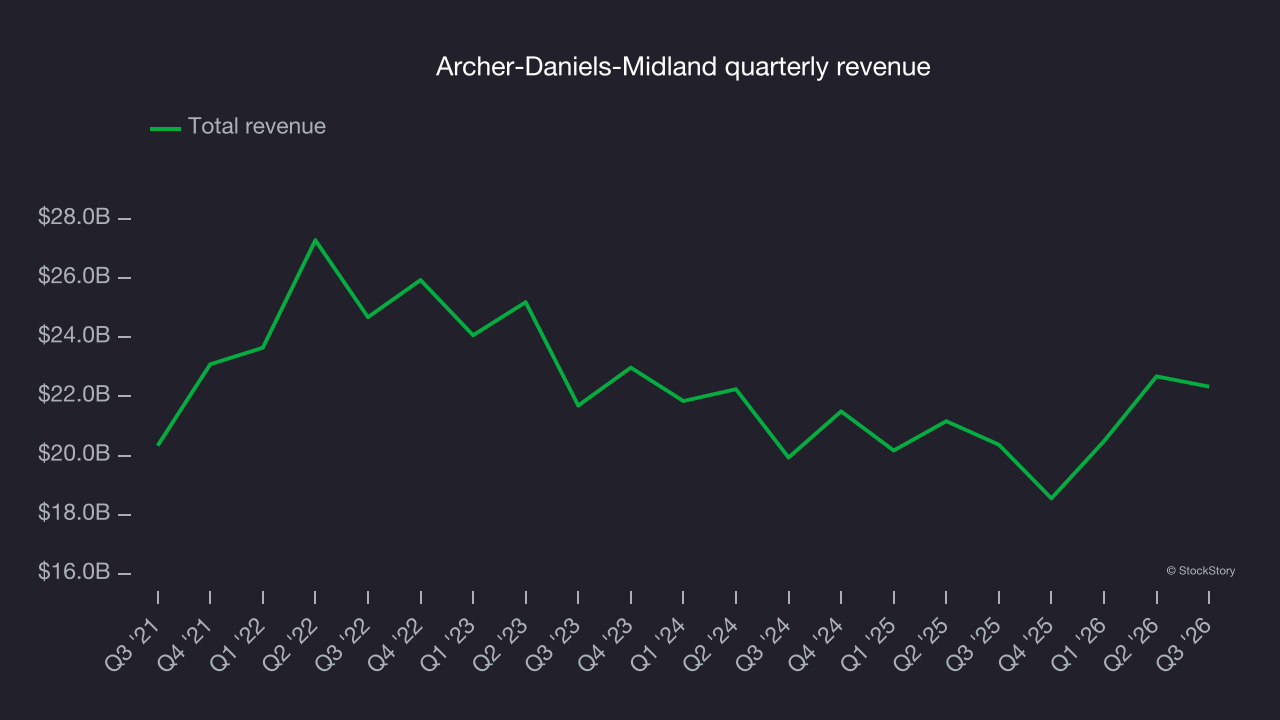
This quarter, Archer-Daniels-Midland’s revenue grew by 9.6% year on year to $22.34 billion, missing Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 12% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is particularly noteworthy for a company of its scale and suggests its newer products will fuel better top-line performance.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s revealing because it accounts for all operating and capital expenses, making it difficult to manipulate.
Archer-Daniels-Midland has shown mediocre cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 3%, below expectations for a consumer staples business.
Archer-Daniels-Midland’s margin dropped by 5.2 percentage points over the last year. That decline, combined with its uninspiring margin, puts the company in a difficult position, and shareholders are likely hoping it can reverse course. If the trend continues, it could signal it’s becoming a more capital-intensive business.
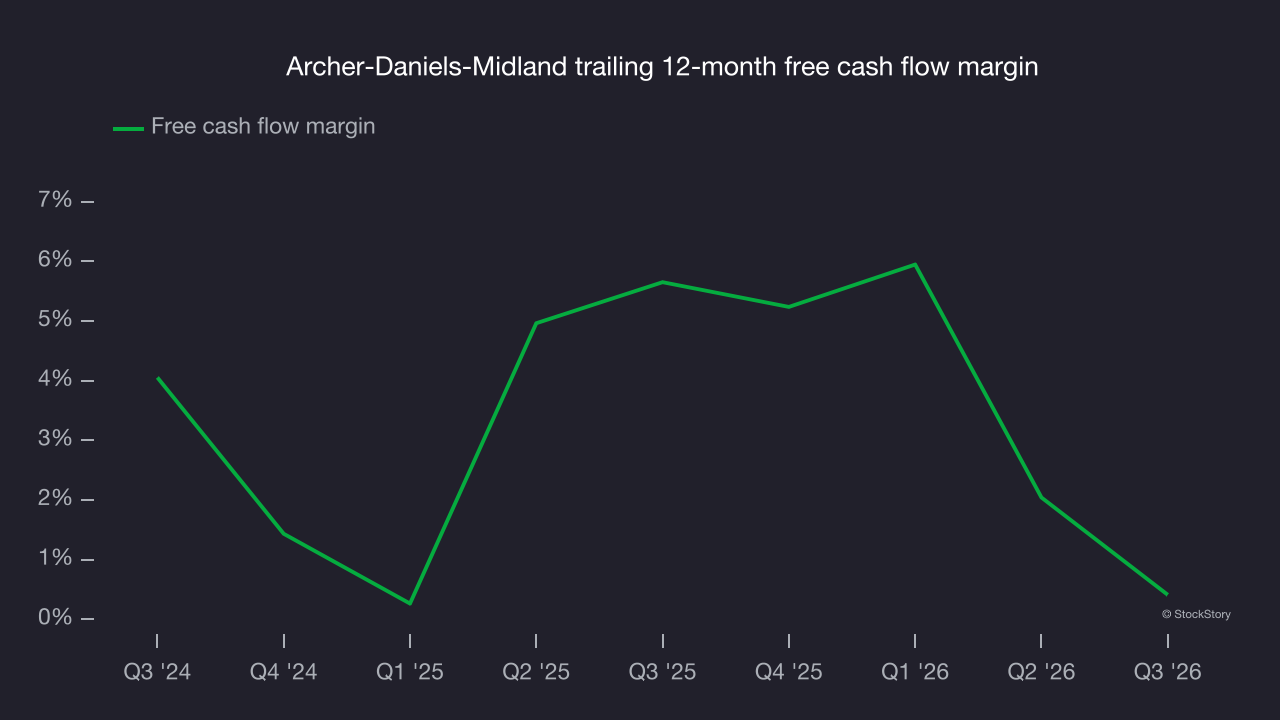
Archer-Daniels-Midland broke even on a free cash flow basis in Q3. The company’s cash profitability deteriorated, falling 6.6 percentage points from the same quarter last year, suggesting its historical struggles have persisted.
Key takeaways from Archer-Daniels-Midland’s Q3 results
Archer-Daniels-Midland’s EBITDA came in well above analysts’ consensus estimates, and EPS also topped Wall Street’s consensus. Those were key positives in an otherwise mixed quarter: Gross margin missed expectations, and revenue fell slightly short of Wall Street’s consensus. Shares remained flat at $75.52 immediately after the results.
When evaluating Archer-Daniels-Midland as an investment, consider the bigger picture of valuation, business quality and the latest earnings. Read our free full research report for more on these factors.