Computer processor maker AMD (NASDAQ: AMD) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 44.7% year on year to $13.38 billion. In addition, next quarter’s revenue guidance of $17 billion at the midpoint exceeded analysts’ consensus estimates by a surprising 4.4%. Its non-GAAP profit of $2.09 per share was 7.7% above analysts’ consensus estimates.
For more on AMD, read our free full research report.
AMD (AMD) Q3 2026 highlights:
- Revenue $13.38 billion vs S&P analysts’ consensus estimates of $13.11 billion (44.7% year-on-year growth, 2% beat)
- Adjusted EPS $2.09 vs S&P analysts’ consensus estimates of $1.94 (7.7% beat)
- Adjusted EBITDA $4.16 billion vs analysts’ consensus estimates of $3.52 billion (31.1% margin, 18.4% beat)
- Revenue guidance $17 billion at the midpoint for Q4 2026, above analysts’ consensus estimates of $16.29 billion
- Operating margin 21.2%, up from 13.7% in the same quarter last year
- Free cash flow margin 4.1%, down from 20.6% in the same quarter last year
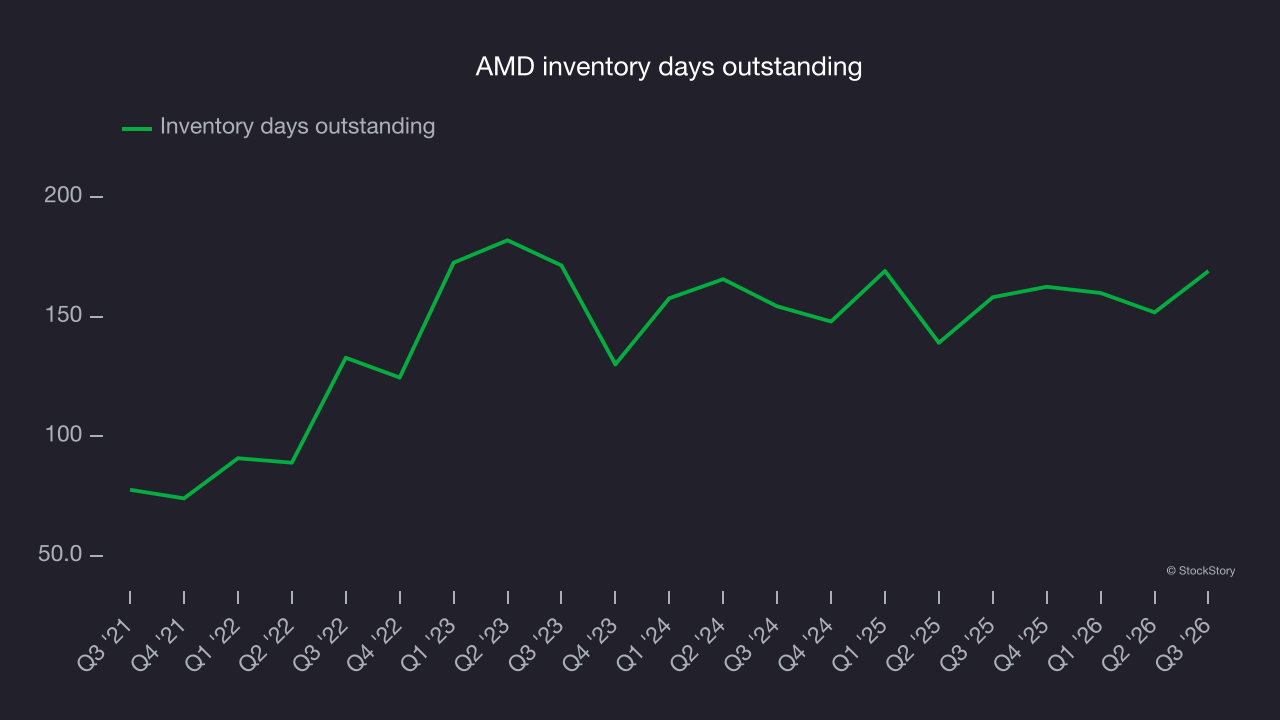
- Inventory days outstanding 169, up from 152 in the previous quarter
- Market capitalization $762.1 billion
“We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year,” said Dr. Lisa Su, AMD chair and CEO. “Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production. With our leadership product portfolio and deep customer and supply chain relationships, we are confident in our ability to sustain very strong revenue growth and expanding profitability over the coming years.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. AMD’s revenue grew at a strong 25.1% compounded annual growth rate over the last five years. Its growth beat the average semiconductor company and shows its offerings resonate with customers. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
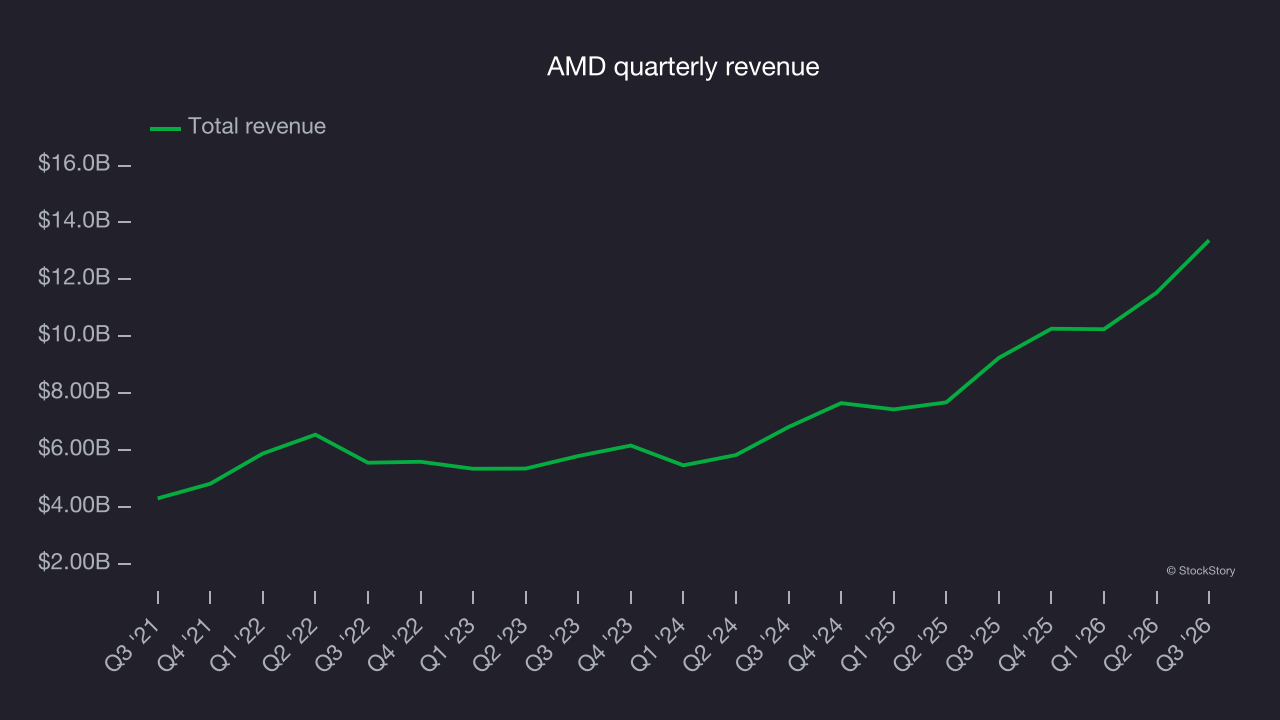
Long-term growth matters the most, but within semiconductors, a half-decade historical view may miss new demand cycles or industry trends like artificial intelligence. AMD’s annualized revenue growth of 36.8% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated.
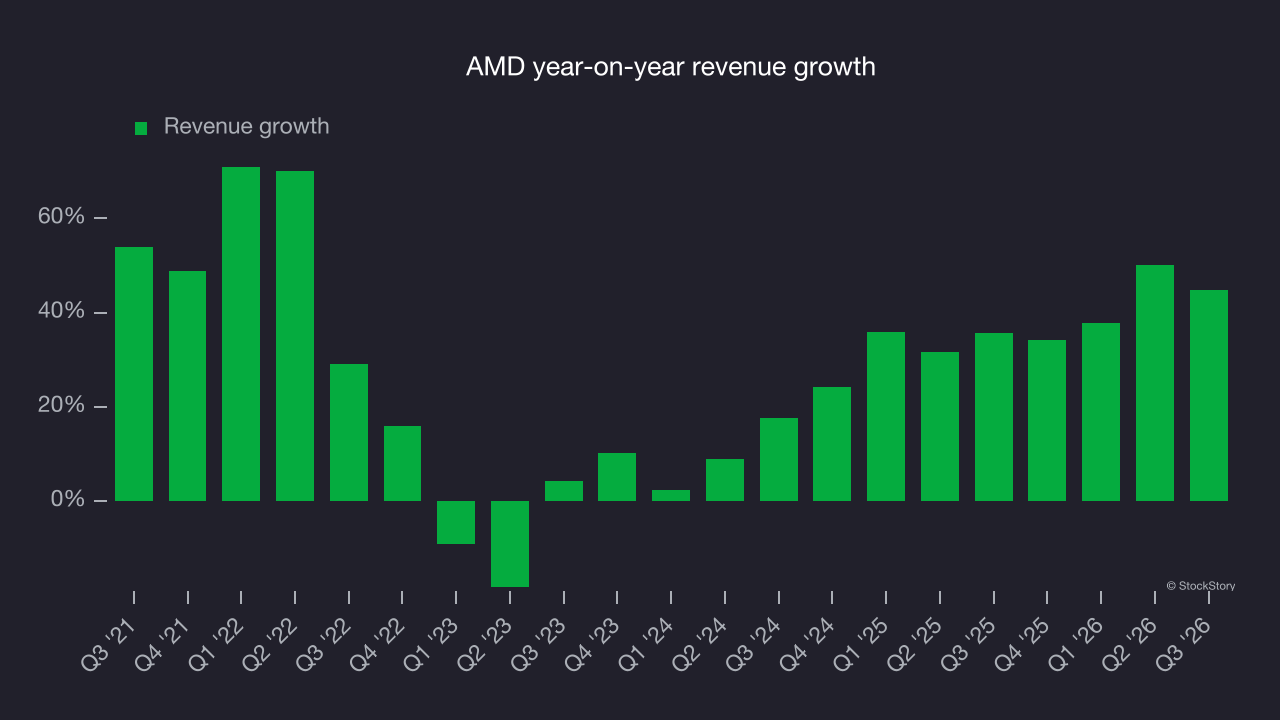
This quarter, AMD reported strong year-on-year revenue growth of 44.7%, and its $13.38 billion of revenue beat Wall Street’s consensus estimates by 2%. Beyond the beat, this marks 13 straight quarters of growth, showing that the current upcycle has lasted longer than the typical 8 to 10 quarters. Management is guiding for a 65.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 75.4% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is notable for a company of its scale and suggests its newer products and services will spur better revenue performance.
Product demand & outstanding inventory
Days inventory outstanding, or DIO, is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, AMD’s DIO came in at 169, which is 24 days above its five-year average, suggesting that the company’s inventory has grown beyond past levels.
Key takeaways from AMD’s Q3 results
AMD delivered a solid Q3, with EPS beating analysts’ consensus estimates and operating income also topping Wall Street’s consensus. An increase in inventory was the only concern in an otherwise positive quarter. Shares surged 6.7% to $516.90 immediately after the report.
AMD may have had a good quarter, but that alone doesn’t determine whether the stock is a buy. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in this stock. For more on AMD, read our full research report here (it’s free).