

Semiconductor testing company FormFactor (NASDAQ: FORM) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 38.4% year on year to $280.5 million. Revenue guidance for next quarter was $285 million at the midpoint, 2.6% above analysts’ consensus estimates. Its non-GAAP profit of $1.04 per share was 20.5% above analysts’ consensus estimates.
For more on FormFactor, read our free full research report.
FormFactor (FORM) Q3 2026 highlights:
- Revenue $280.5 million vs S&P analysts’ consensus estimates of $270.5 million (38.4% year-on-year growth, 3.7% beat)
- Adjusted EPS $1.04 vs S&P analysts’ consensus estimates of $0.86 (20.5% beat)
- Adjusted operating income $94.07 million vs analysts’ consensus estimates of $76.33 million (33.5% margin, 23.2% beat)
- Revenue guidance $285 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $277.9 million
- Adjusted EPS guidance $0.95 at the midpoint for Q4 2026, above analysts’ consensus estimates of $0.81
- Operating margin 29.1%, up from 8.9% in the same quarter last year
- Free cash flow margin 23.1%, up from 9.6% in the same quarter last year
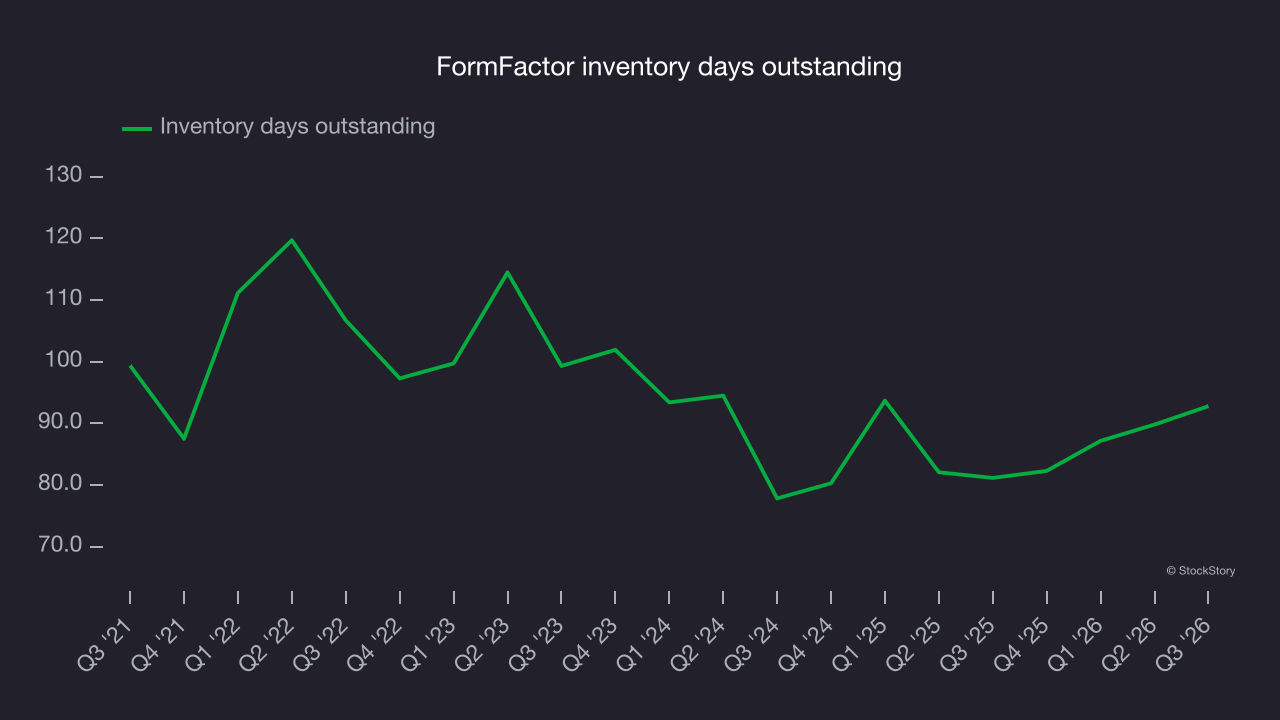
- Inventory days outstanding 93, up from 90 in the previous quarter
- Market capitalization $8.35 billion
“FormFactor continued its strong momentum during the third quarter, delivering growth in revenue, gross margin, and earnings per share that exceeded the high end of our guidance,” said Mike Slessor, CEO of FormFactor, Inc. “These results underscore the strength of our diversified leadership position at the intersection of high-performance compute and advanced packaging, and our ability to meet rising customer demand by increasing output within our existing manufacturing footprint.”
Revenue growth
Reviewing a company’s top-line performance can reveal insights into its business quality. Growth can signal it’s capitalizing on a new product or emerging industry trend. FormFactor’s annualized revenue growth rate of 14.9% over the last two years was decent for a semiconductor business. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
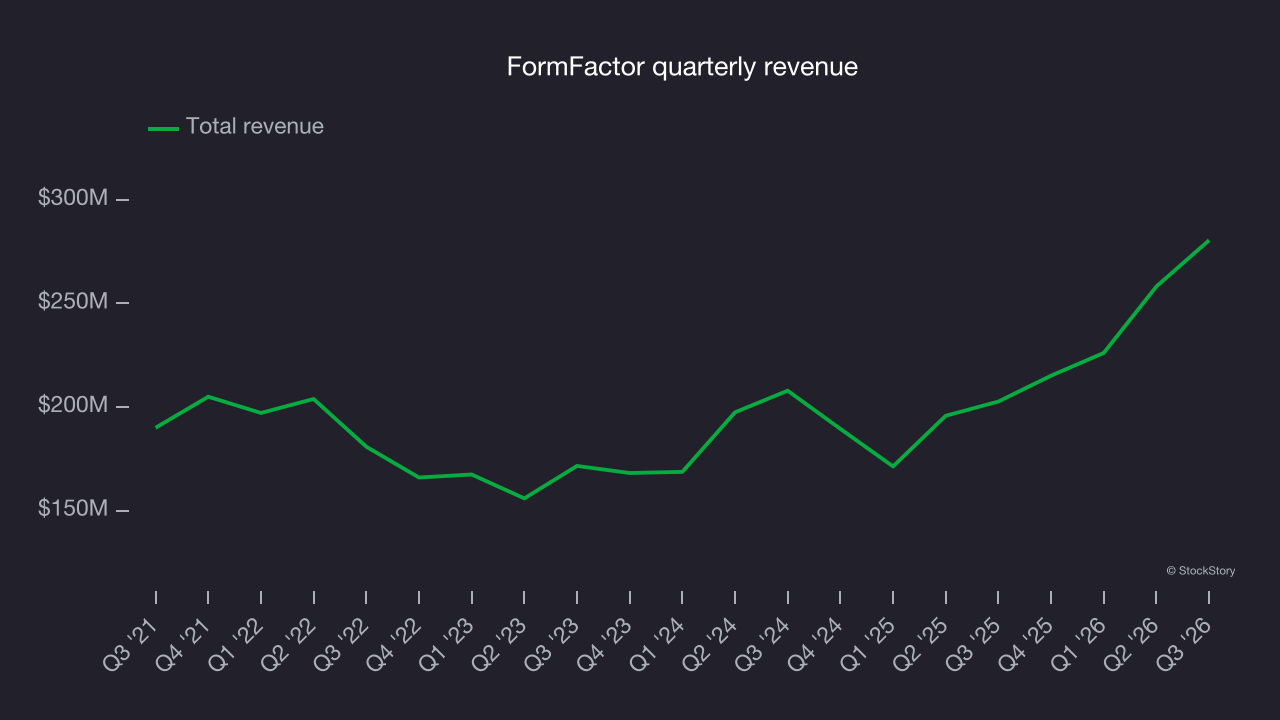
Long-term growth matters most, but within semiconductors, a half-decade historical view may miss new demand cycles or industry trends like AI. FormFactor’s annualized revenue growth of 14.9% over the last two years is above its five-year trend, suggesting some bright spots. 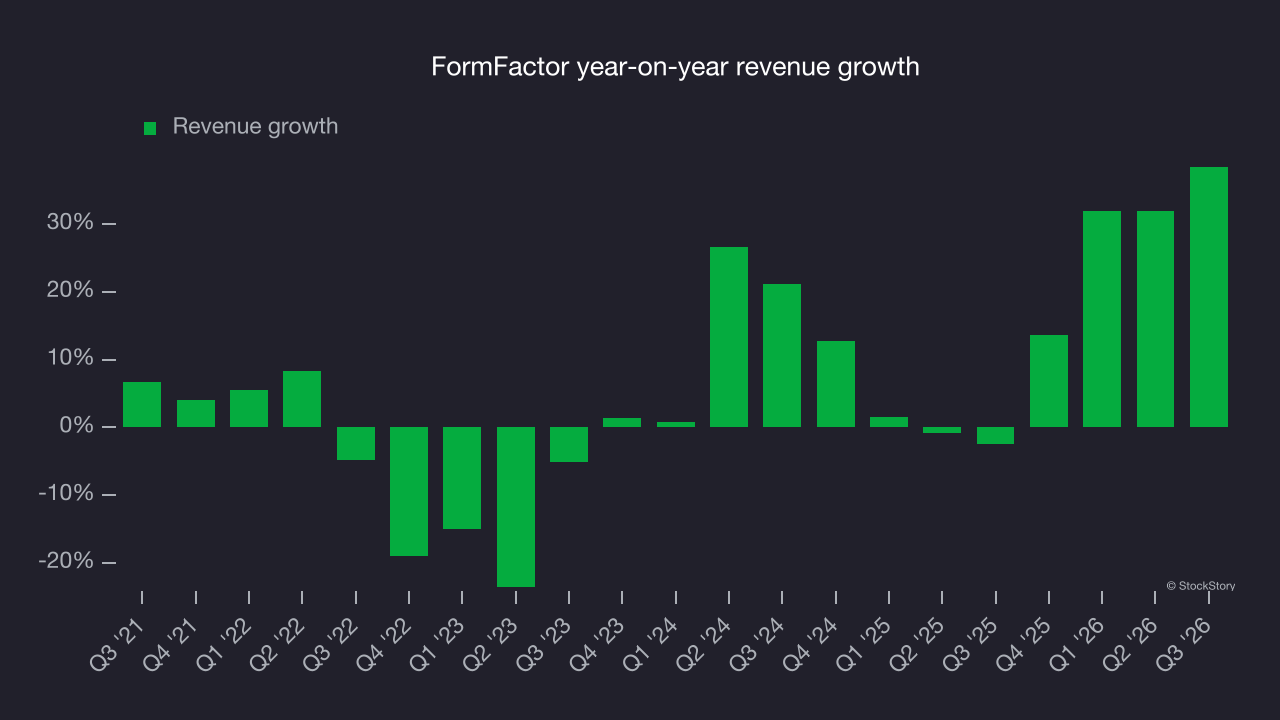
This quarter, FormFactor reported year-on-year revenue growth of 38.4%, and its $280.5 million in revenue exceeded Wall Street’s consensus estimates by 3.7%. Beyond the beat, this marks 4 straight quarters of growth, implying that FormFactor is in the middle of its cycle – a typical upcycle generally lasts 8-10 quarters. Company management is currently guiding for a 32.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 19.5% over the next 12 months, according to S&P. While this projection indicates its newer products and services will fuel better top-line performance, it is still below average for the sector.
Product demand & outstanding inventory
Days Inventory Outstanding (DIO) is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, FormFactor’s DIO came in at 93, which is 2 days below its five-year average. These numbers show that despite the recent increase, there’s no indication of an excessive inventory buildup.
Key takeaways from FormFactor’s Q3 results
FormFactor’s operating income topped Wall Street’s consensus estimates by a wide margin, and EPS also beat analysts’ consensus estimates. Those were important positives for the quarter, but inventory levels increased. Investors were likely hoping for more: Shares plunged 10.5% to $99.35 immediately after the results.
Considering an investment in FormFactor now? When making that decision, it’s important to consider its valuation, business quality and what happened in the latest quarter. For more, read our full research report here (it’s free).



