Flow control equipment manufacturer Flowserve (NYSE: FLS) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 5.4% year on year to $1.24 billion. Its non-GAAP profit of $1.07 per share was 9% above analysts’ consensus estimates.
For more on Flowserve, read our free full research report.
Flowserve (FLS) Q3 2026 highlights:
- Revenue $1.24 billion vs S&P analysts’ consensus estimates of $1.24 billion (5.4% year-on-year growth, in line)
- Adjusted EPS $1.07 vs S&P analysts’ consensus estimates of $0.98 (9% beat)
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $4.15 at the midpoint
- Operating margin 12.5%, up from 6.7% in the same quarter last year
- Free cash flow margin 0%, down from 32.8% in the same quarter last year
- Backlog $3.47 billion at quarter end, up 19.9% year on year
- Market capitalization $9 billion
"Our teams delivered another quarter of meaningful bookings growth, adjusted operating margin expansion, and higher adjusted earnings per share while navigating ongoing Middle East disruption,” said Scott Rowe, Flowserve’s President and Chief Executive Officer. “The Flowserve Business System is helping us translate solid market demand into bookings growth and stronger profitability, with a clear focus on growth, execution, and customer service. The resilience and commitment of our associates around the globe remain instrumental in our ability to deliver for our customers and shareholders.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Flowserve’s revenue grew at a tepid 5.4% compounded annual growth rate over the last five years, an underwhelming result compared with the rest of the industrials sector. Still, there are things to like about Flowserve.
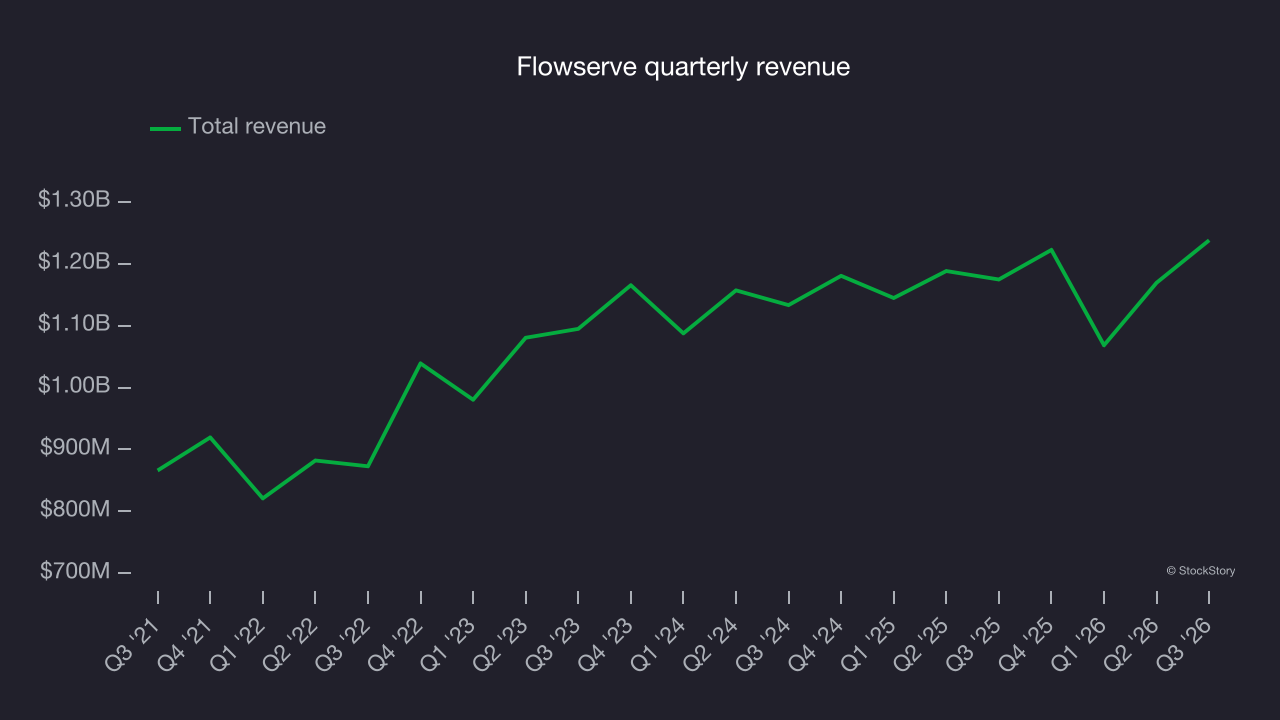
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Flowserve’s recent performance shows its demand has slowed as its annualized revenue growth of 1.7% over the last two years was below its five-year trend. Decelerating revenue growth in the sector is a concern, as it could signal changing consumer tastes aided by low switching costs. 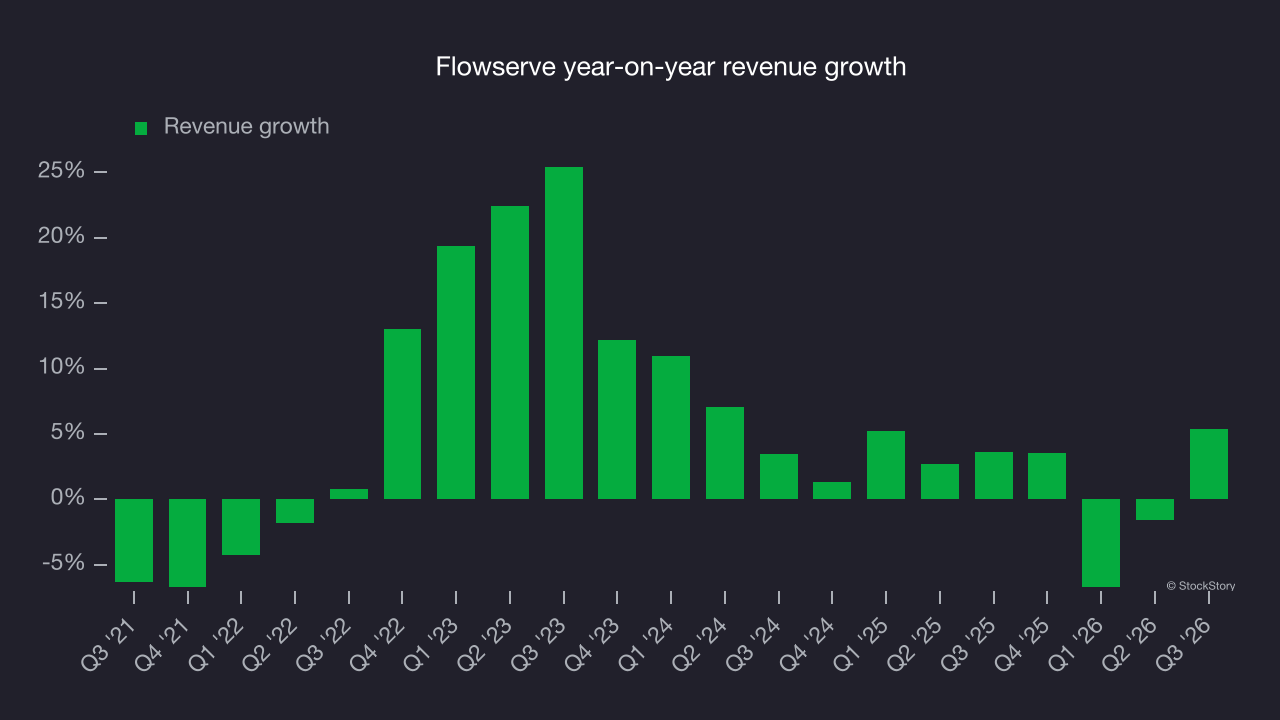
The company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, offers further insight into its revenue dynamics. Flowserve’s backlog reached $3.47 billion in the latest quarter and averaged 8.9% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Flowserve’s products and services but raises concerns about capacity constraints. 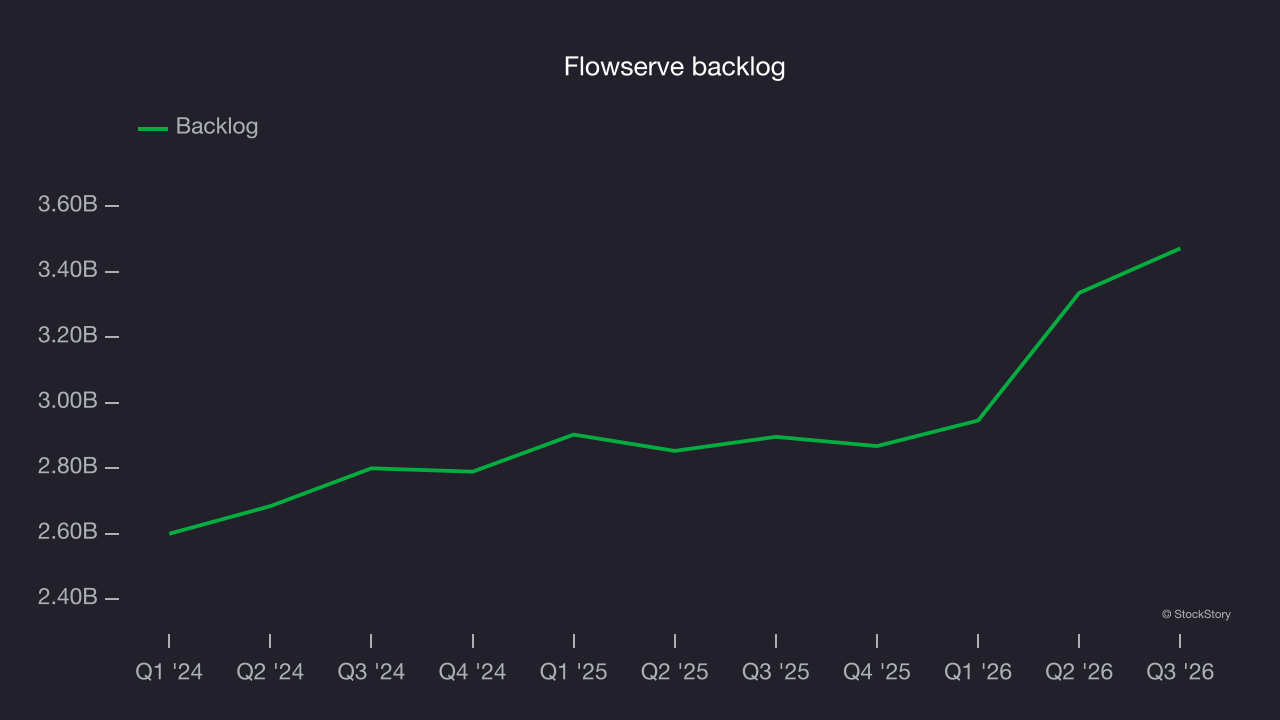
This quarter, Flowserve grew its revenue by 5.4% year on year, and its $1.24 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 9.5% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is noteworthy and suggests its newer products and services will spur better top-line performance.
Operating margin
Flowserve has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 8.8%, higher than the broader industrials sector.
Looking at the trend in its profitability, Flowserve’s operating margin rose by 4.9 percentage points over the last five years, as its revenue growth gave it operating leverage.
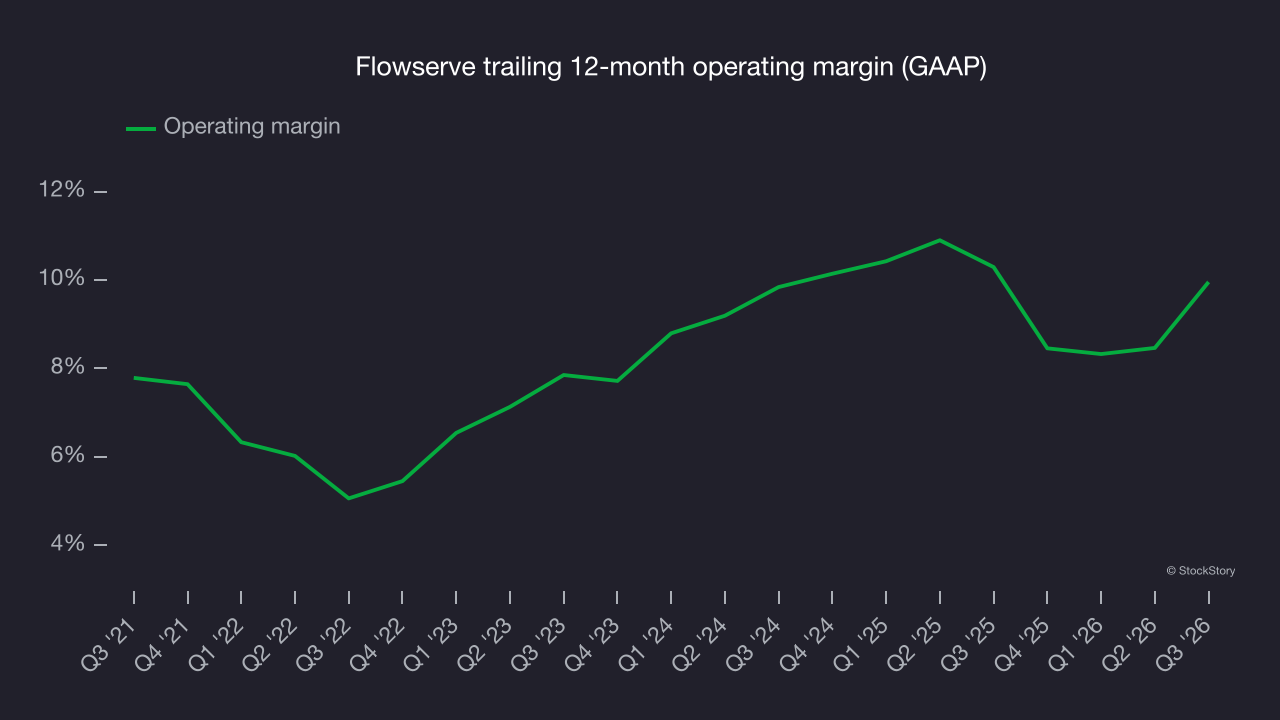
This quarter, Flowserve generated an operating margin of 12.5%, up 5.7 percentage points year on year. The increase was solid. With gross margin declining, the improvement suggests greater efficiency, as operating expenses such as marketing, R&D and administrative overhead grew more slowly than revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Flowserve’s EPS grew at a 22% compounded annual growth rate over the last five years, higher than its 5.4% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
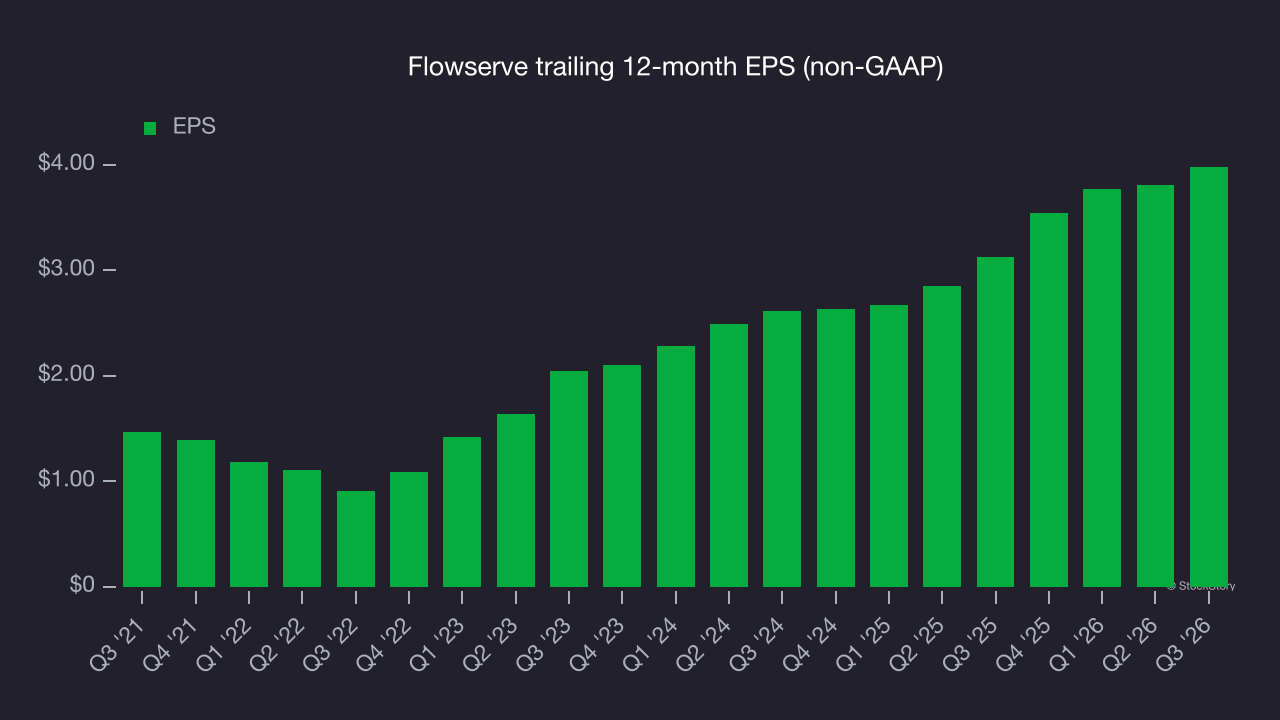
Examining Flowserve’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Flowserve’s operating margin expanded by 4.9 percentage points over the last five years. On top of that, its share count shrank by 2.2%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 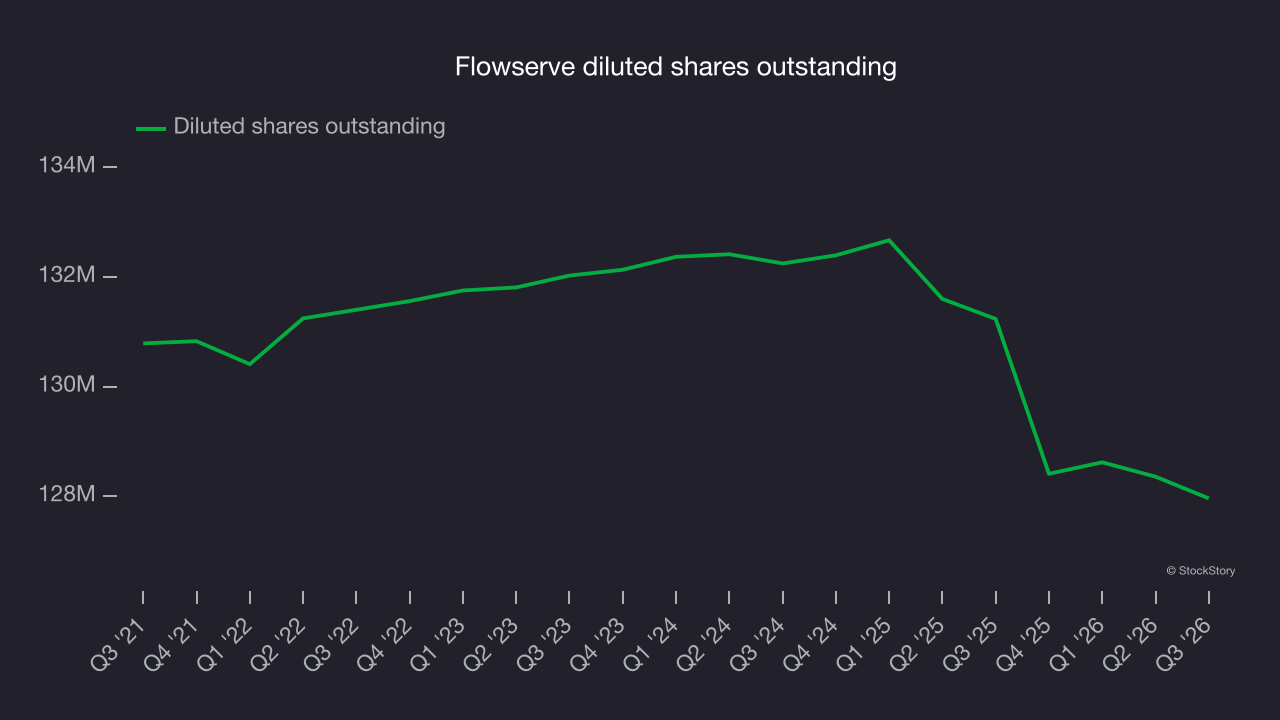
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Flowserve, its two-year annual EPS growth of 23.5% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Flowserve reported adjusted EPS of $1.07, up from $0.90 in the same quarter last year. This result beat analysts’ consensus estimates by 9%. Over the next 12 months, Wall Street expects Flowserve’s full-year EPS to grow 11.9% from $3.98 to $4.45, according to S&P.
Key takeaways from Flowserve’s Q3 results
Flowserve paired an EPS beat with full-year EPS guidance slightly above analysts’ consensus estimates, giving the quarter some clear positives. Shares rose 2.9% to $73.82 immediately after the release.
Flowserve had a positive quarter, but one earnings result doesn’t necessarily make the stock a buy. The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Flowserve, read our free full research report here.