What a fantastic six months it’s been for Park-Ohio. Shares of the company have skyrocketed 62%, hitting $43.48. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Park-Ohio, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Park-Ohio not exciting?
We’re happy investors have made money, but we’re passing on Park-Ohio for now. Here are three reasons why there are better opportunities than PKOH, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
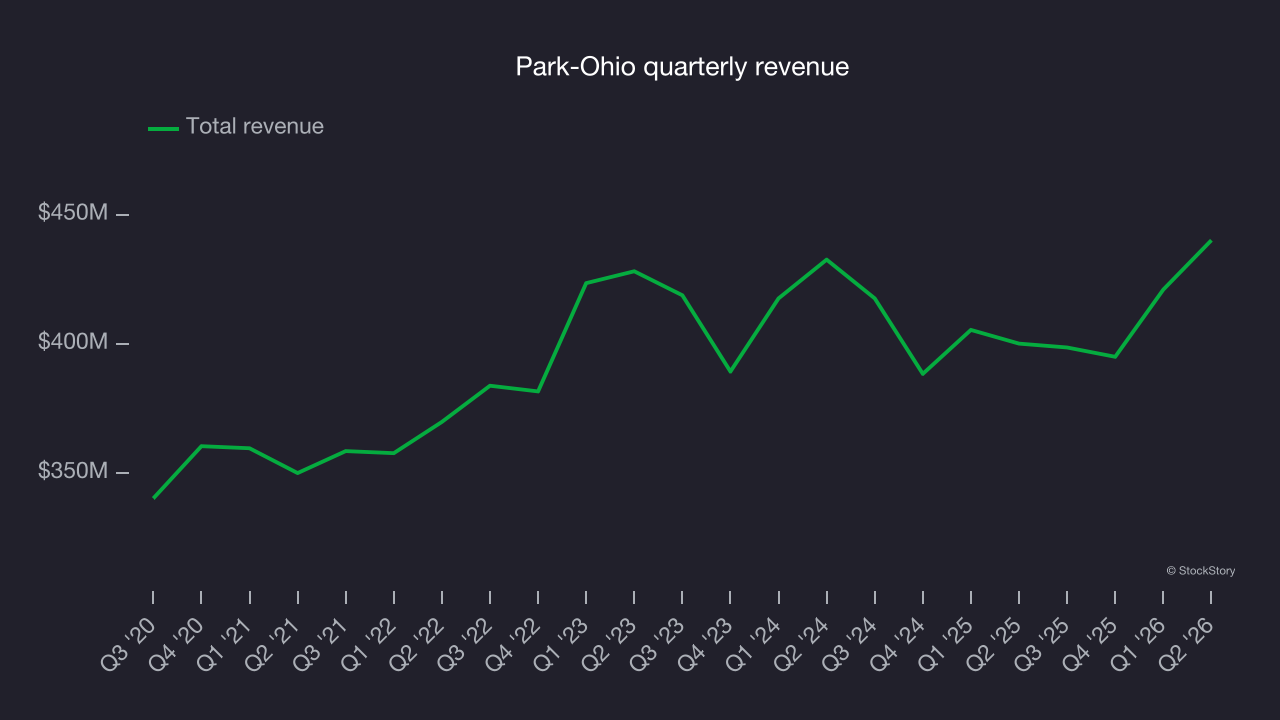
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Park-Ohio’s 3.2% annualized revenue growth over the last five years was sluggish. This was below our standard for the industrials sector.
2. EPS took a dip over the last two years
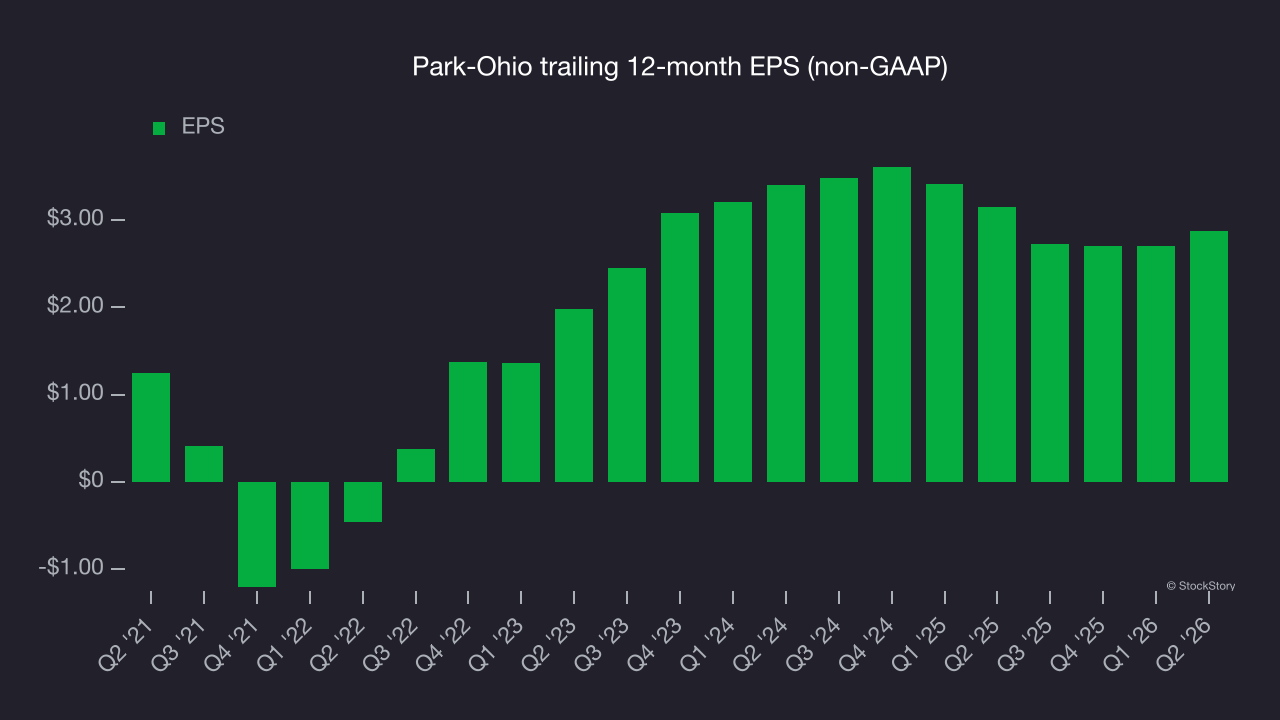
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Sadly for Park-Ohio, its EPS declined by 8% annually over the last two years while its revenue was flat. This tells us the company struggled to adjust to choppy demand.
3. Breakeven free cash flow limits reinvestment potential
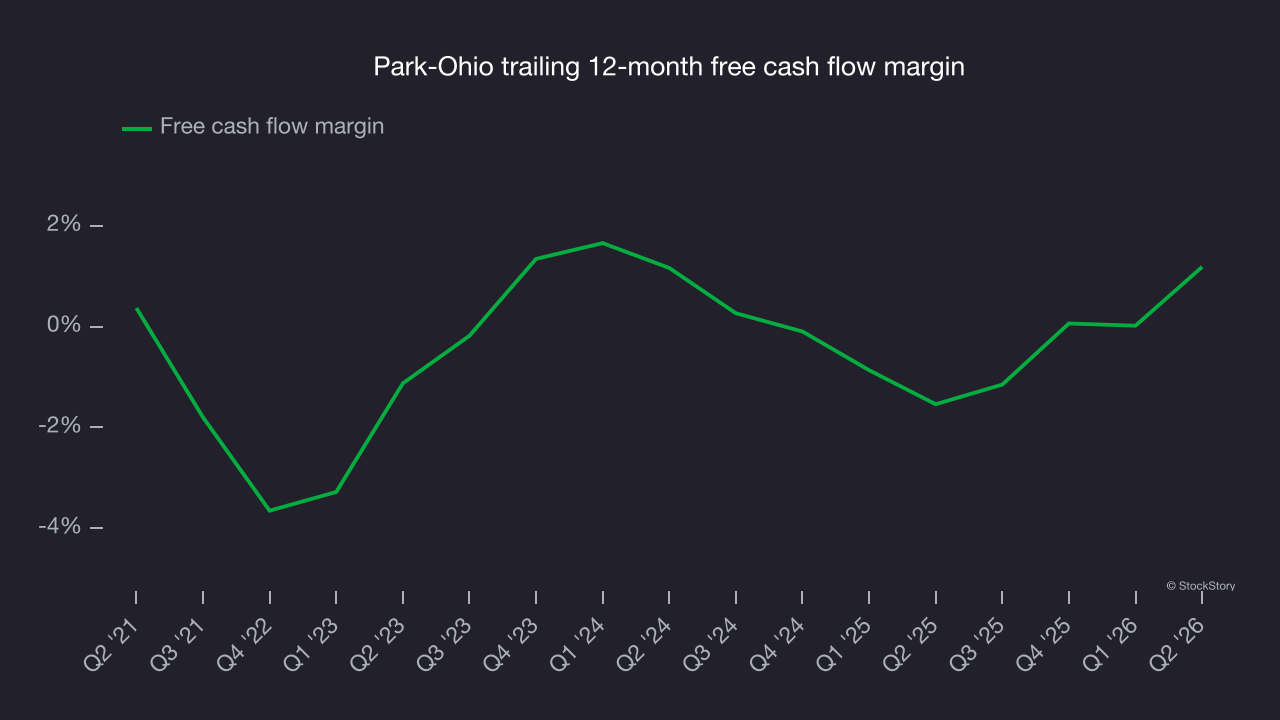
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Park-Ohio broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
Final judgment
Park-Ohio isn’t a terrible business, but it doesn’t pass our bar. After the recent surge, the stock trades at 12.2× forward P/E (or $43.48 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at one of our top digital advertising picks.
Stocks we would buy instead of Park-Ohio
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.