
Regional banking company Columbia Banking System (NASDAQ: COLB) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 20% year on year to $695 million. Its non-GAAP profit of $0.82 per share was 6.8% above analysts’ consensus estimates.
Is now the time to buy Columbia Banking System? Find out by accessing our full research report, it’s free.
Columbia Banking System (COLB) Q3 2026 highlights:
- Net Interest Income: $615 million vs analyst estimates of $603.2 million (21.8% year-on-year growth, 2% beat)
- Net Interest Margin: 4.1% vs analyst estimates of 4% (11.3 basis point beat)
- Revenue: $695 million vs analyst estimates of $688.3 million (20% year-on-year growth, 1% beat)
- Efficiency Ratio: 53.1% vs analyst estimates of 53.9% (83.4 basis point beat)
- Adjusted EPS: $0.82 vs analyst estimates of $0.77 (6.8% beat)
- Tangible Book Value per Share: $18.10 vs analyst estimates of $19.31 (2.5% year-on-year decline, 6.2% miss)
- Market Capitalization: $8.26 billion
"Our third quarter performance demonstrates the benefits of consistent execution and active balance sheet management," said Clint Stein, Chairman, CEO & President. "By remaining focused on relationship-driven growth, prudent loan and deposit pricing, and operational discipline, we continued to improve our profitability while maintaining strong credit quality and returning excess capital. Over the past year, we returned over $1 billion to our shareholders through dividends and share repurchases, completing our existing buyback authorization in the process. Our Board of Directors has authorized a new $1.2 billion share repurchase program, reflecting confidence in our long-term strategy and our outlook for continued excess capital generation. We remain focused on growing our franchise in ways that strengthen customer relationships, enhance the quality of our balance sheet, and support attractive long-term returns for our shareholders."
Company overview
Created through the merger of two Pacific Northwest banking institutions with deep regional roots, Columbia Banking System (NASDAQ: COLB) operates Umpqua Bank, providing commercial, consumer, and wealth management services across eight western states.
Sales growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income. Thankfully, Columbia Banking System’s 35.2% annualized revenue growth over the last five years was incredible. Its growth beat the average banking company and shows its offerings resonate with customers.
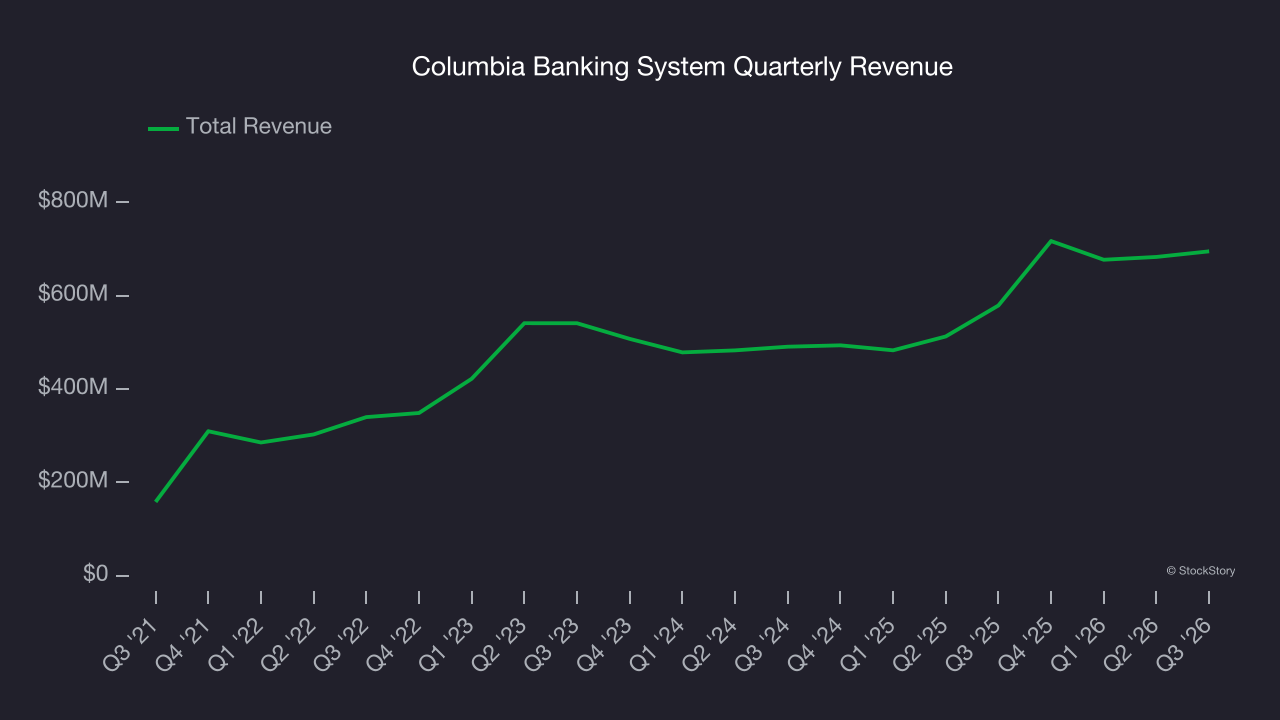
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Columbia Banking System’s annualized revenue growth of 18.9% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 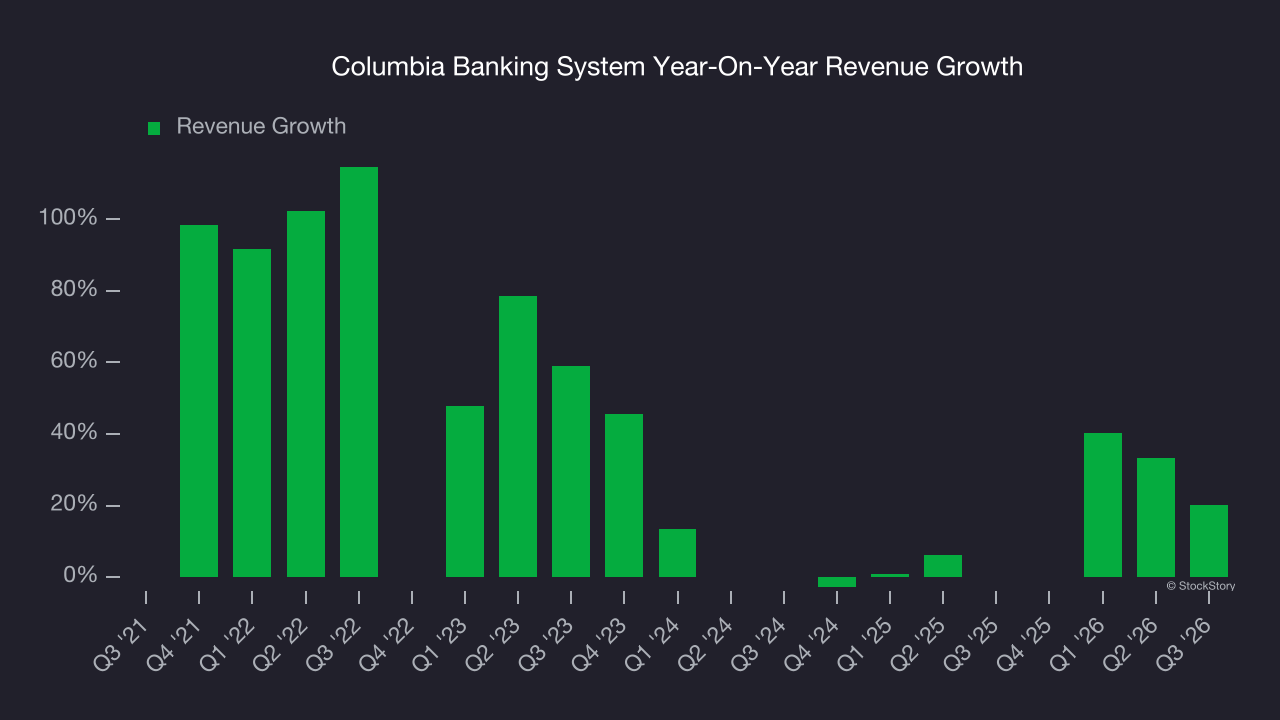 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Columbia Banking System reported robust year-on-year revenue growth of 20%, and its $695 million of revenue topped Wall Street estimates by 1%.
Net interest income made up 86.6% of the company’s total revenue during the last five years, meaning Columbia Banking System barely relies on non-interest income to drive its overall growth.
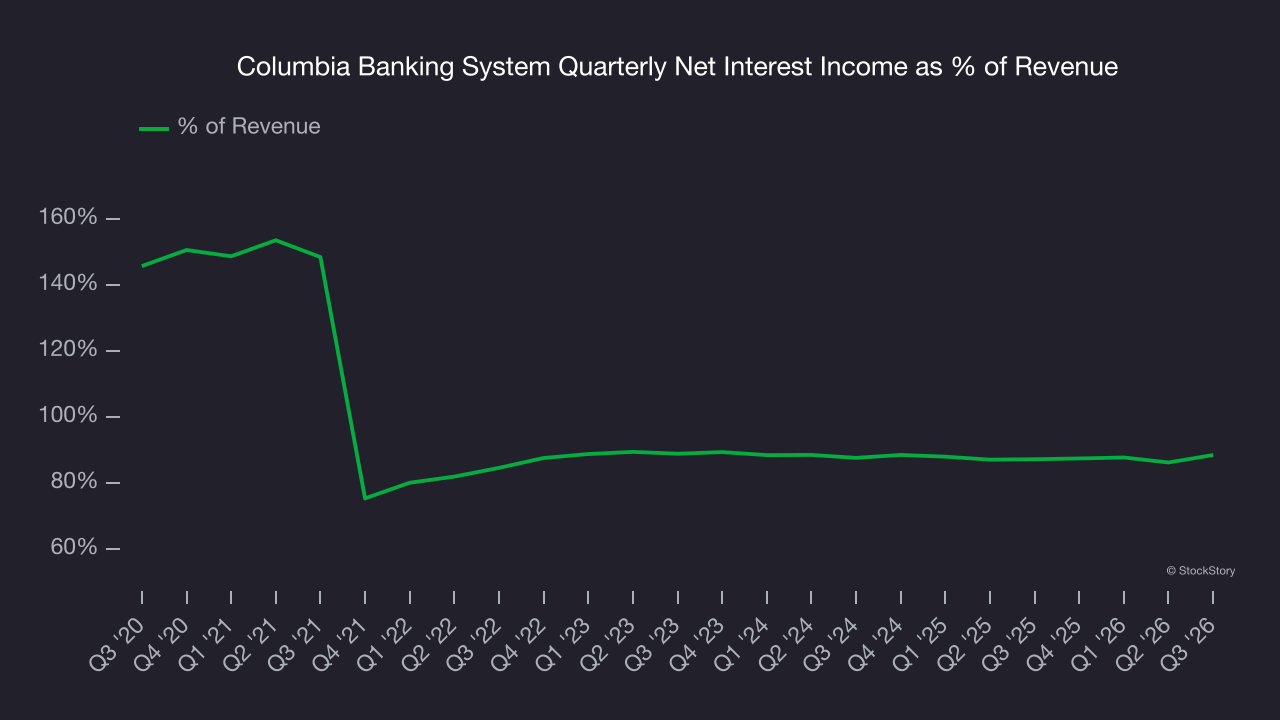
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Tangible book value per share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This explains why tangible book value per share (TBVPS) stands as the premier banking metric. TBVPS strips away questionable intangible assets, revealing concrete per-share net worth that investors can trust. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
Columbia Banking System’s TBVPS declined at a 2.9% annual clip over the last five years. TBVPS has stabilized recently as it was flat over the last two years at about $18.10 per share.
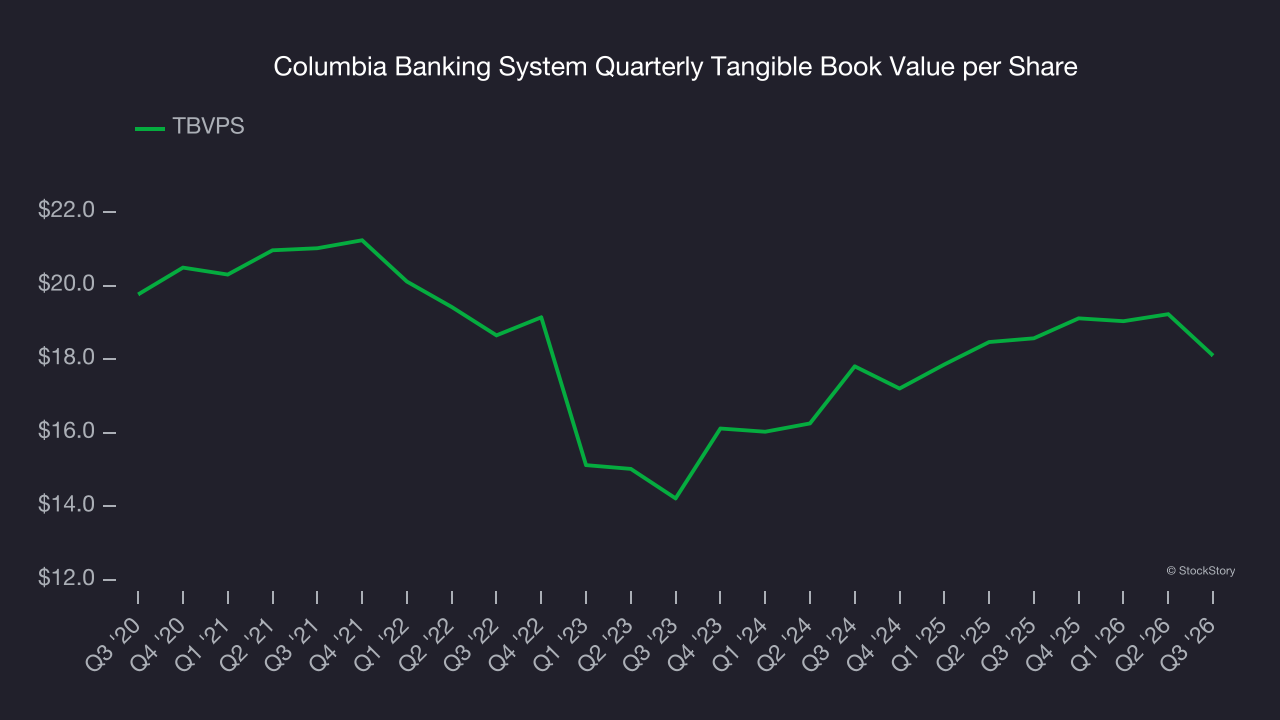
Over the next 12 months, Consensus estimates call for Columbia Banking System’s TBVPS to grow by 15% to $20.81, decent growth rate.
Key takeaways from Columbia Banking System’s Q3 results
It was encouraging to see Columbia Banking System beat analysts’ net interest income expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. On the other hand, its tangible book value per share missed. Overall, this quarter could have been better. The stock remained flat at $29.87 immediately following the results.
So do we think Columbia Banking System is an attractive buy at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).