
Independent Bank has been treading water for the past six months, recording a small return of 3.9% while holding steady at $81.31.
Is there a buying opportunity in Independent Bank, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Independent Bank not exciting?
We don’t have much confidence in Independent Bank. Here are three reasons why INDB doesn’t excite us, plus one stock we’d rather own.
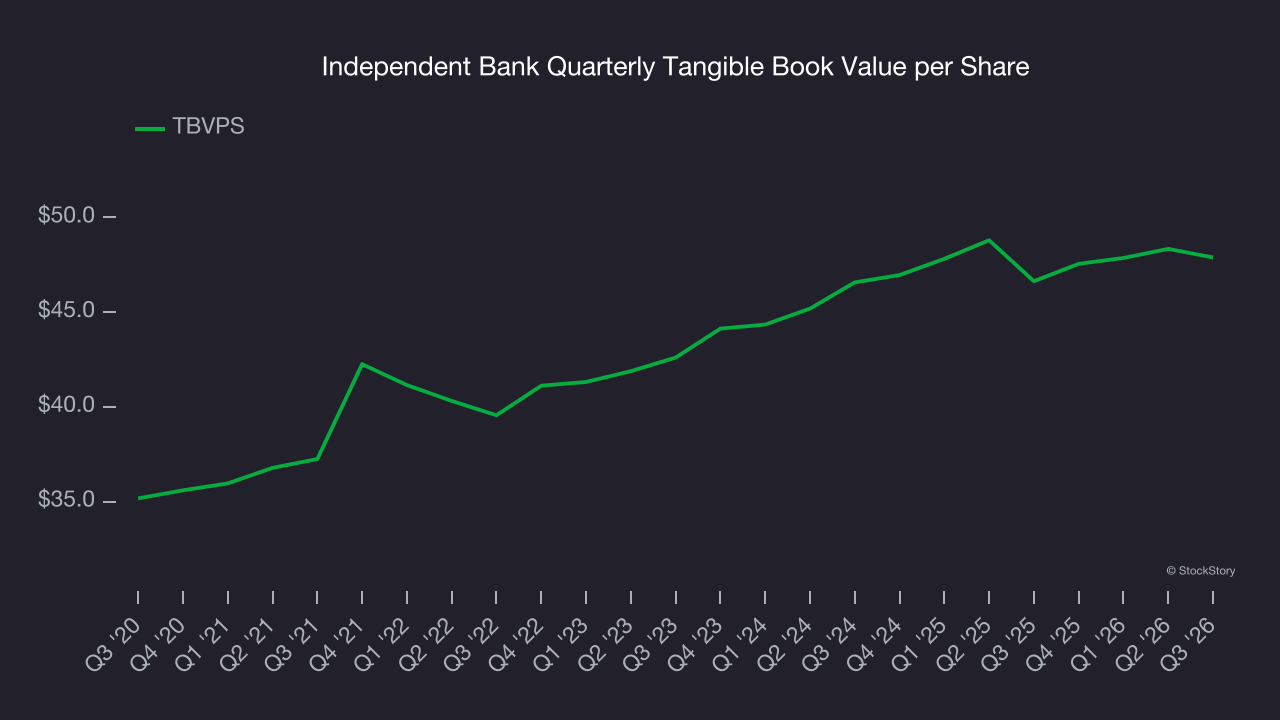
1. Substandard TBVPS growth indicates limited asset expansion
We consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation.
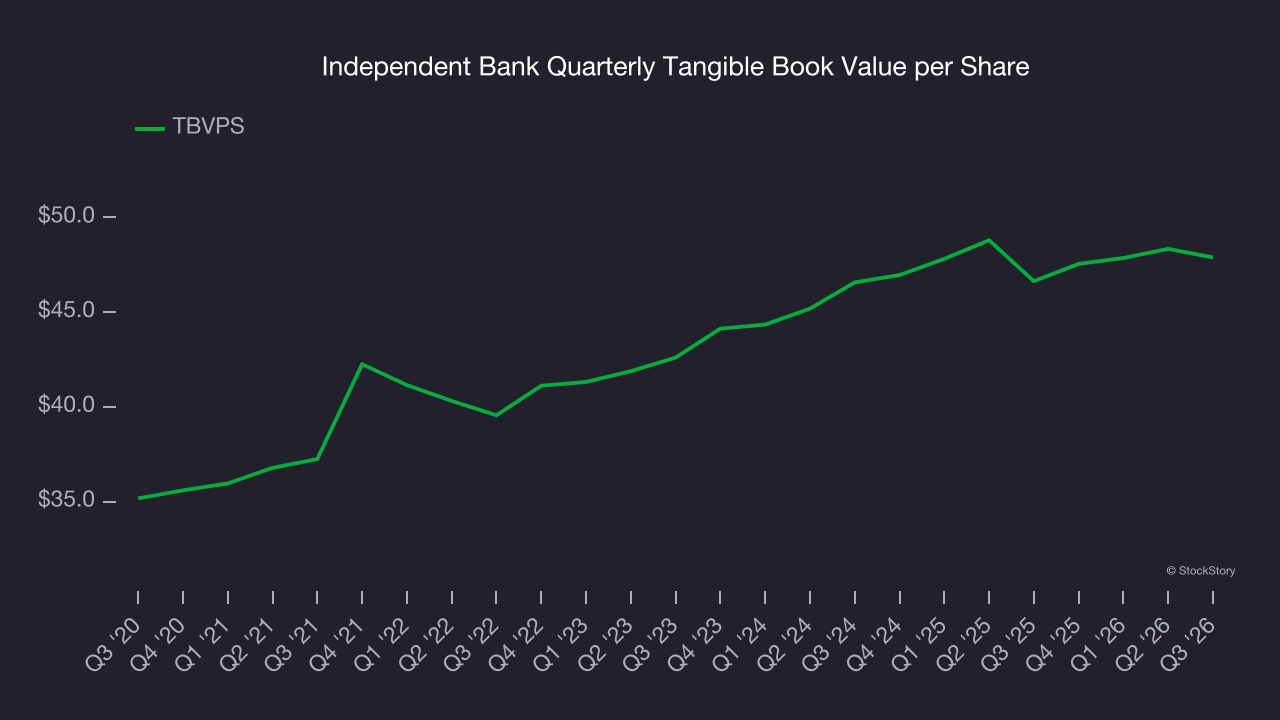
Although Independent Bank’s TBVPS increased by 5.2% annually over the last five years, growth has recently decelerated to a weak 1.4% over the past two years (from $46.57 to $47.89 per share).
2. Projected TBVPS growth is slim
A bank’s tangible book value per share (TBVPS) increases when it generates higher net interest margins and keeps credit losses low, allowing it to compound shareholder value over time.
Over the next 12 months, Consensus estimates call for Independent Bank’s TBVPS to grow by 8.7% to $52.06, a paltry growth rate.
3. Previous growth initiatives haven’t impressed
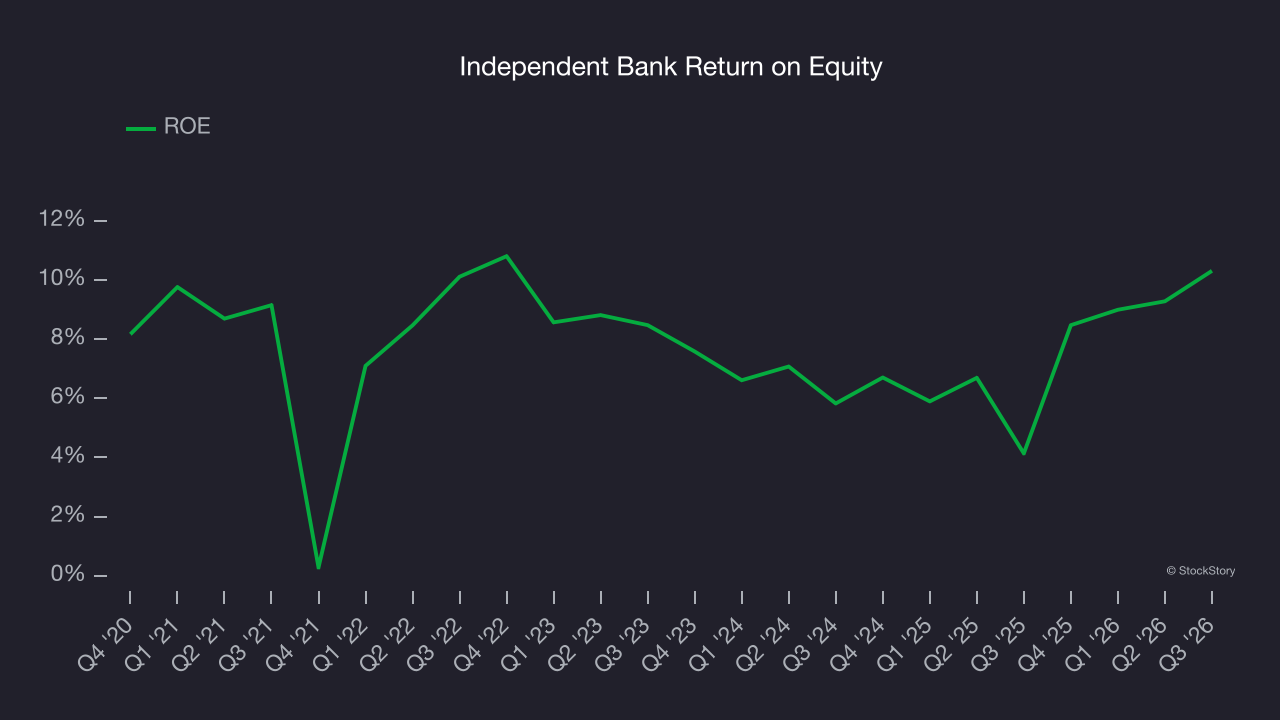
Return on equity (ROE) measures how effectively banks generate profit from each dollar of shareholder equity - a critical funding source. High-ROE institutions typically compound shareholder wealth faster over time through retained earnings, share repurchases, and dividend payments.
Over the last five years, Independent Bank has averaged an ROE of 7.5%, uninspiring for a company operating in a sector where the average shakes out around 10%.
Final judgment
Independent Bank isn’t a terrible business, but it isn’t one of our picks. That said, the stock currently trades at 1.1× forward P/B (or $81.31 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at the most dominant software business in the world.
Stocks we would buy instead of Independent Bank
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.