
As the Q2 earnings season wraps, let’s dig into this quarter’s best and worst performers in the discount retailer industry, including Ross Stores (NASDAQ: ROST) and its peers.
Discount retailers understand that many shoppers love a good deal, and they focus on providing excellent value to shoppers by selling general merchandise at major discounts. They can do this because of unique purchasing, procurement, and pricing strategies that involve scouring the market for trendy goods or buying excess inventory from manufacturers and other retailers. They then turn around and sell these snacks, paper towels, toys, clothes, and myriad other products at highly enticing prices. Despite the unique draw and lure of discounts, these discount retailers must also contend with the secular headwinds of online shopping and challenged retail foot traffic in places like suburban strip malls.
The 5 discount retailer stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 0.8% while next quarter’s revenue guidance was 2.8% above.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Ross Stores (NASDAQ: ROST)
Selling excess inventory or overstocked items from other retailers, Ross Stores (NASDAQ: ROST) is an off-price concept that sells apparel and other goods at prices much lower than department stores.
Ross Stores reported revenues of $6.26 billion, up 13.3% year on year. This print exceeded analysts’ expectations by 1.8%. Overall, it was an exceptional quarter for the company with a beat of analysts’ EPS estimates and a solid beat of analysts’ gross margin estimates.
Mr. Conroy commented, "Looking ahead, we exited the second quarter with building momentum and are excited for the plans we have in place entering the Fall season. Despite facing significantly more challenging year-over-year comparisons in the back half, we are raising our outlook for both the third and fourth quarters. Comparable store sales are now expected to increase 6% to 7% in the third quarter and 4% to 5% in the fourth quarter. If the second half of 2026 performs in line with these sales projections, our earnings per share ranges for the third and fourth quarters are projected to be $1.75 to $1.83 and $2.17 to $2.26, respectively."
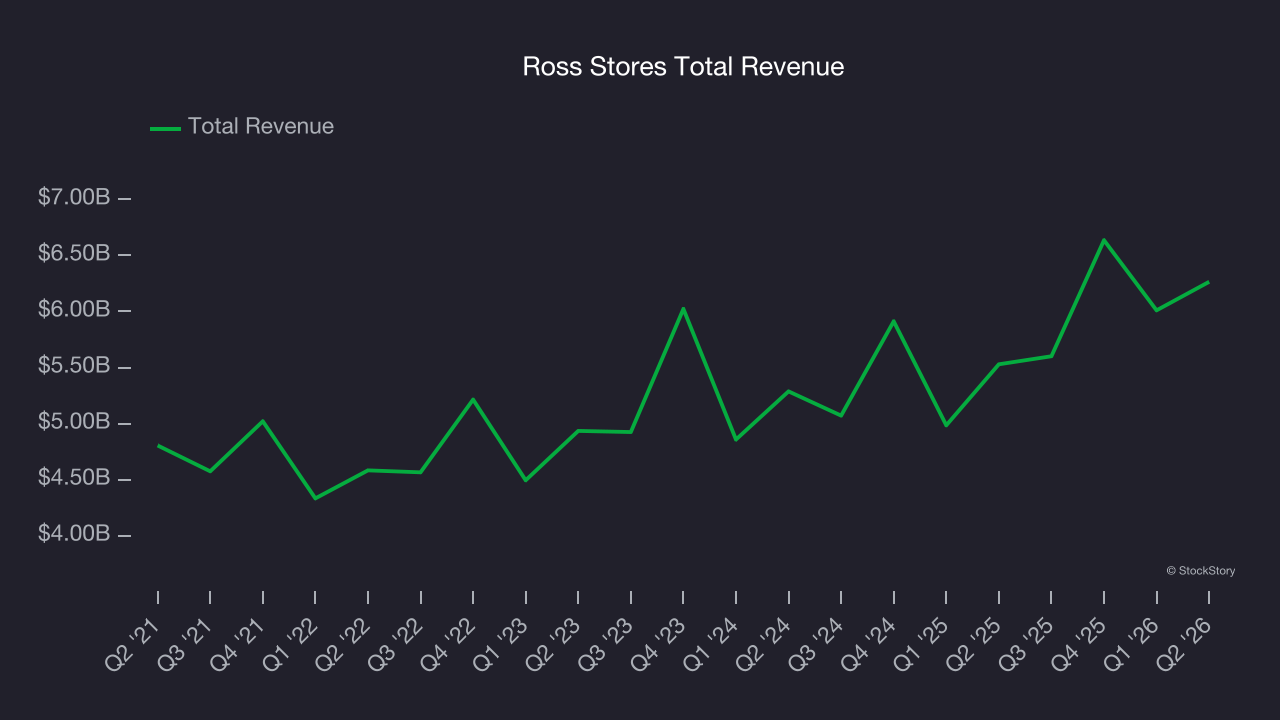
Interestingly, the stock is up 3.6% since reporting and currently trades at $237.24.
Best Q2: Five Below (NASDAQ: FIVE)
Often facilitating a treasure hunt shopping experience, Five Below (NASDAQ: FIVE) is an American discount retailer that sells a variety of products from mobile phone cases to candy to sports equipment for largely $5 or less.
Five Below reported revenues of $1.26 billion, up 22.9% year on year, outperforming analysts’ expectations by 3.7%. The business had a stunning quarter with EPS guidance for next quarter exceeding analysts’ expectations and a solid beat of analysts’ gross margin estimates.
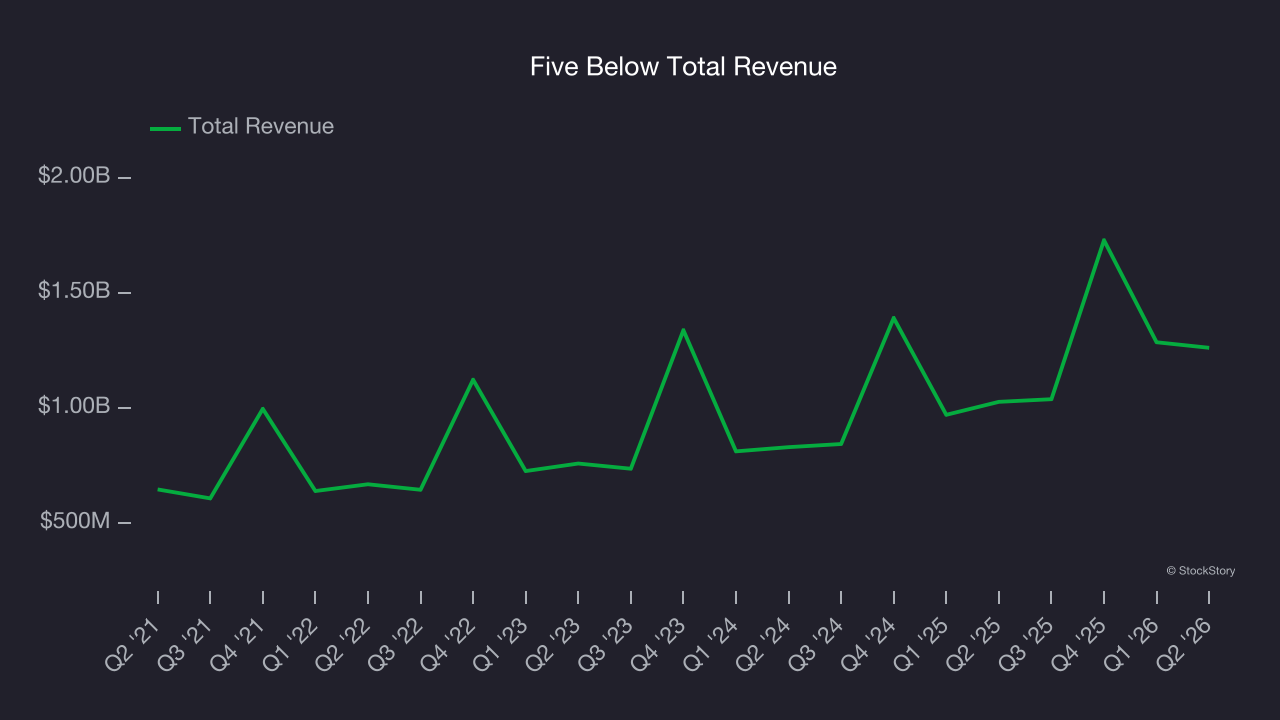
Five Below scored the biggest analyst estimate beat, highest guidance raise, and fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 8.6% since reporting. It currently trades at $222.29.
Is now the time to buy Five Below? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: TJX (NYSE: TJX)
Initially based on a strategy of buying excess inventory from manufacturers or other retailers, TJX (NYSE: TJX) is an off-price retailer that sells brand-name apparel and other goods at prices much lower than department stores.
TJX reported revenues of $15.18 billion, up 5.4% year on year, in line with analysts’ expectations. It was a slower quarter as it posted EPS guidance for next quarter missing analysts’ expectations and full-year EPS guidance slightly missing analysts’ expectations.
TJX delivered the slowest revenue growth among its peers. As expected, the stock is down 2.7% since the results and currently trades at $146.75.
Read our full analysis of TJX’s results here.
Ollie's (NASDAQ: OLLI)
Often located in suburban or semi-rural shopping centers, Ollie’s Bargain Outlet (NASDAQ: OLLI) is a discount retailer that acquires excess inventory then sells at meaningful discounts.
Ollie's reported revenues of $741.3 million, up 9.1% year on year. This result missed analysts’ expectations by 1.2%. In spite of that, it was a very strong quarter as it recorded an impressive beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
Ollie's had the weakest performance against analyst estimates and weakest full-year guidance update in the group. The stock is up 29.4% since reporting and currently trades at $93.61.
Read our full, actionable report on Ollie's here, it’s free.
Burlington (NYSE: BURL)
Founded in 1972 as a discount coat and outerwear retailer, Burlington Stores (NYSE: BURL) is now an off-price retailer that has broadened into general apparel, footwear, and home goods.
Burlington reported revenues of $3.00 billion, up 11% year on year. This number came in 0.8% below analysts’ expectations. Aside from that, it was a satisfactory quarter as it also produced a beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations significantly.
Burlington had the weakest guidance update of the whole group. The stock is down 17.7% since reporting and currently trades at $258.38.
Read our full, actionable report on Burlington here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.