Sally Beauty trades at $16.05 and has moved in lockstep with the market. Its shares have returned 20.8% over the last six months while the S&P 500 has gained 16.3%.
Is now the time to buy Sally Beauty, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Sally Beauty Will Underperform?
We don’t have much confidence in Sally Beauty. Here are three reasons you should be careful with SBH, plus one stock we’d rather own.
1. Lack of New Stores, a Headwind for Revenue
A retailer’s store count influences how much it can sell and how quickly revenue can grow.
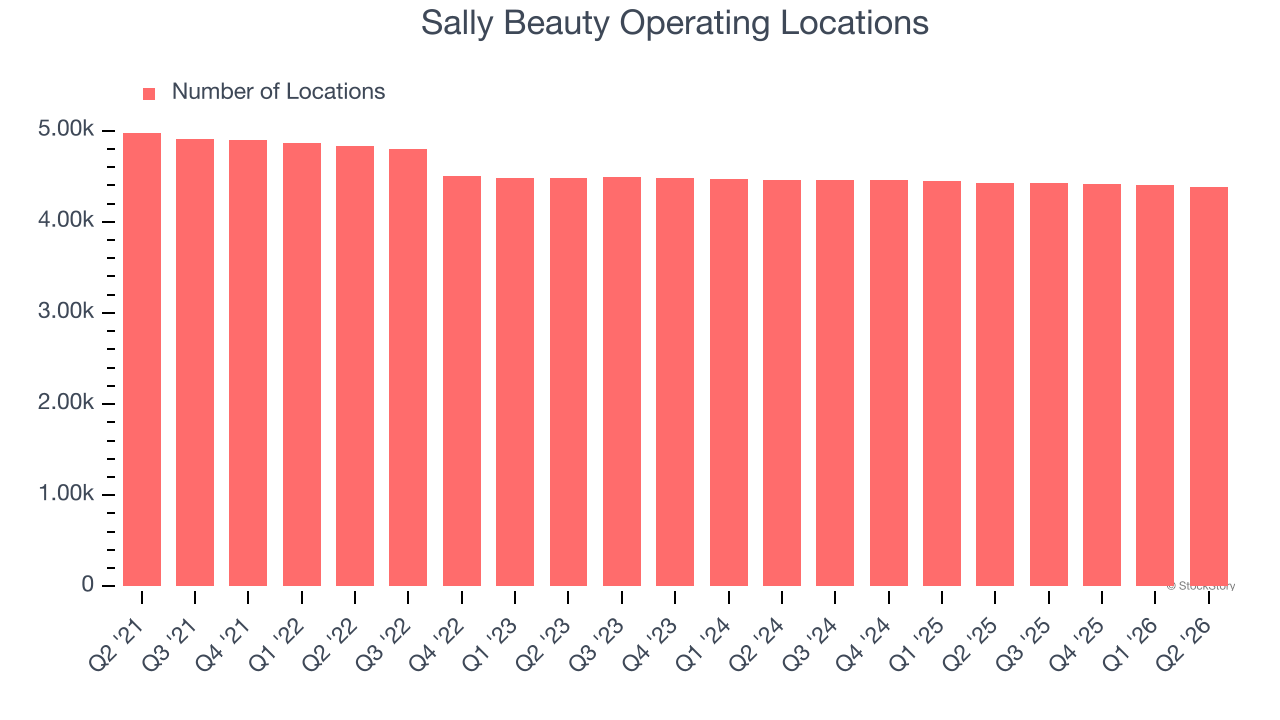
Sally Beauty operated 4,386 locations in the latest quarter, and over the last two years, has kept its store count flat while other consumer retail businesses have opted for growth.
When a retailer keeps its store footprint steady, it usually means demand is stable and it’s focusing on operational efficiency to increase profitability.
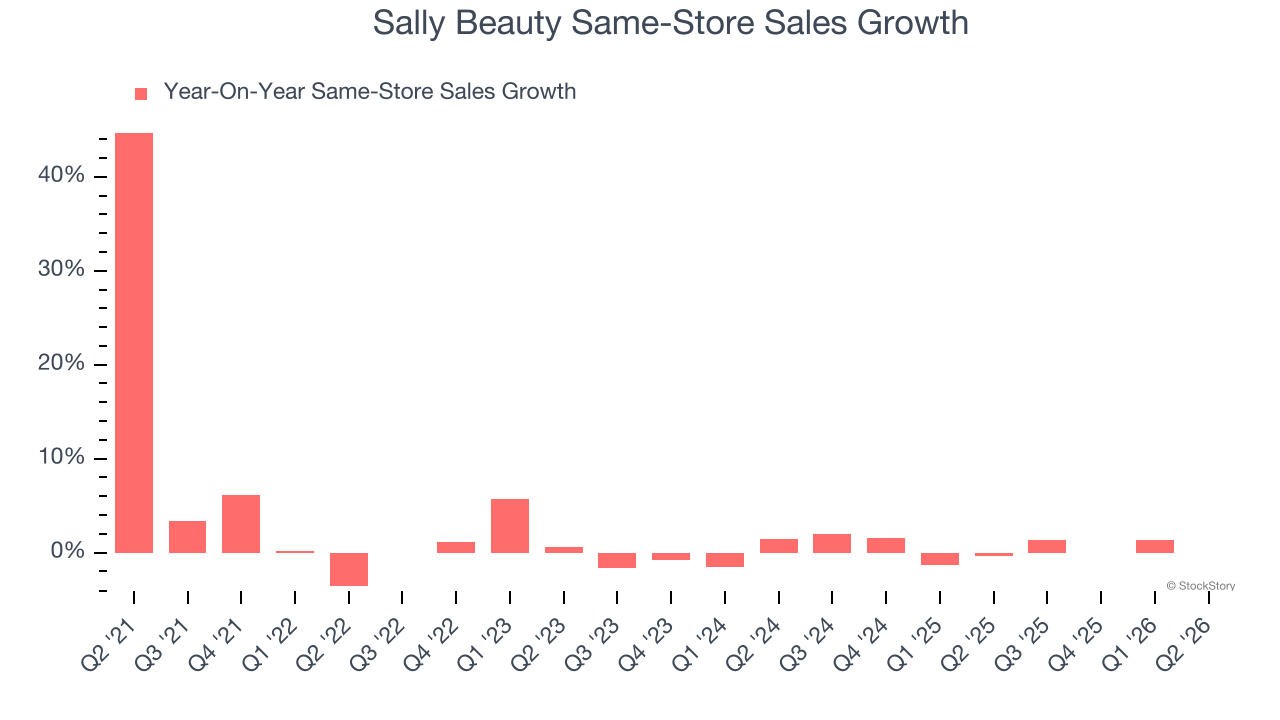
2. Flat Same-Store Sales Indicate Weak Demand
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Sally Beauty’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat.
3. Fewer Distribution Channels Limit Its Ceiling
With $3.73 billion in revenue over the past 12 months, Sally Beauty is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers.
Final Judgment
Sally Beauty falls short of our quality standards. That said, the stock currently trades at 7.5× forward P/E (or $16.05 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Like More Than Sally Beauty
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.