
Since April 2026, NOV has been in a holding pattern, posting a small return of 0.7% while floating around $18.91. The stock also fell short of the S&P 500’s 16.3% gain during that period.
Is now the time to buy NOV, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is NOV Not Exciting?
We’re cautious about NOV. Here are three reasons why there are better opportunities than NOV, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
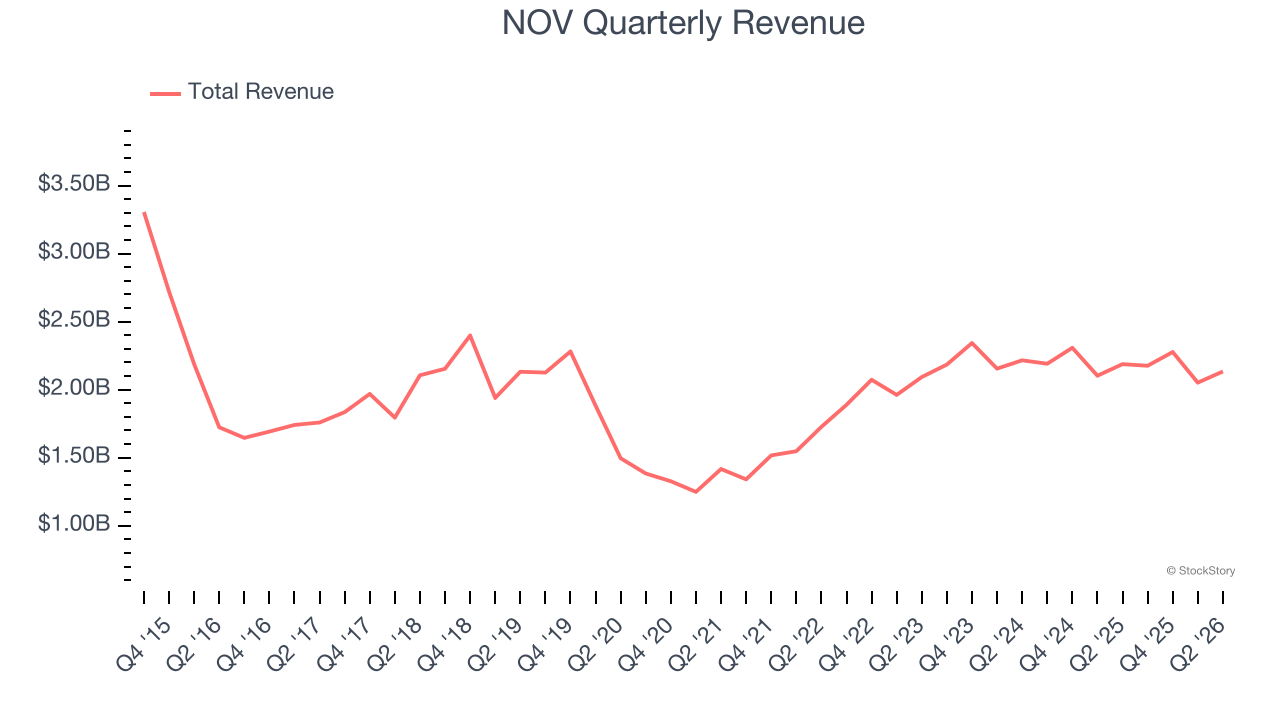
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Over the last five years, NOV grew its sales at a mediocre 9.9% compounded annual growth rate. This fell short of our benchmark for the energy upstream and integrated energy sector.
2. Low Gross Margin Reveals Weak Structural Profitability
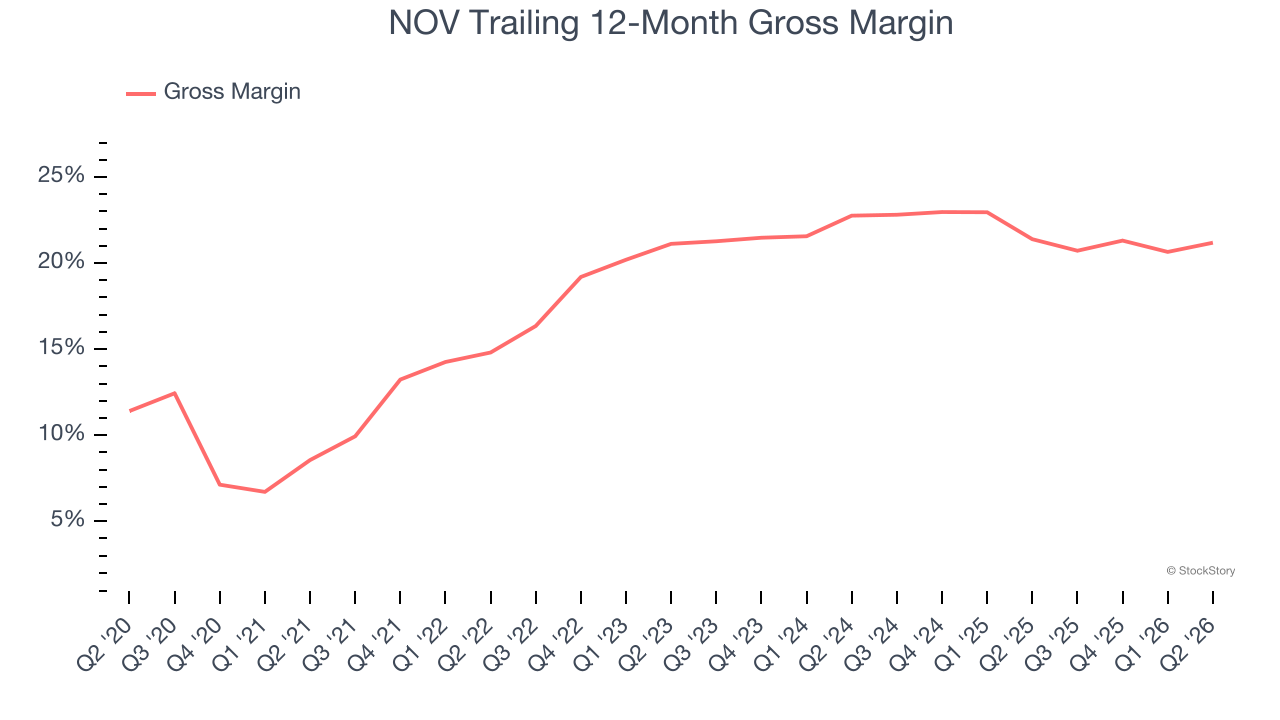
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
NOV, which averaged 20.6% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
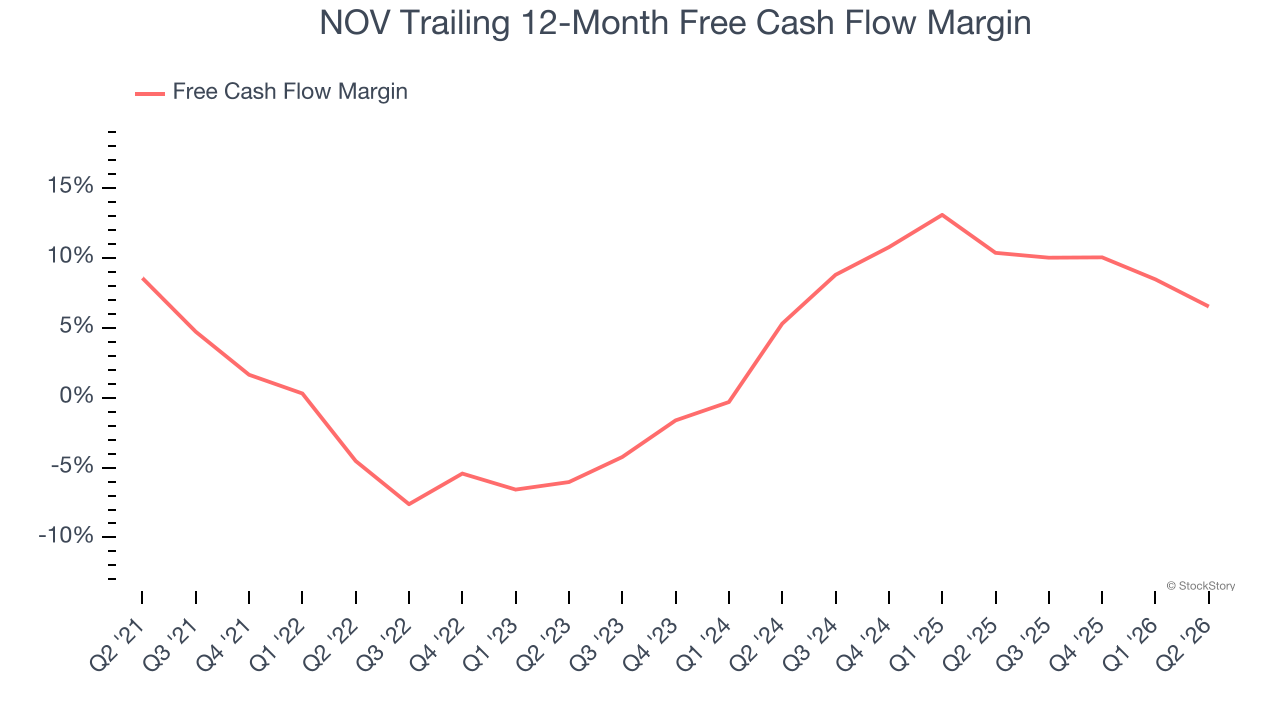
NOV has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.9%, below what we’d expect for an upstream and integrated energy business.
Final Judgment
NOV isn’t a terrible business, but it doesn’t pass our bar. With its shares lagging the market recently, the stock trades at 16.8× forward P/E (or $18.91 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of NOV
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.